
Both invoice financing and invoice factoring effectively turn unpaid invoices into cash straight away, but the mechanisms are different and the implications for your customer are too.
- Factoring is a sale: you sell the invoice to a factoring company (the factor), who pays you out most of the value of the invoice and then collects from your customer (who will often know about it).
- Invoice financing is a loan: you borrow against the value of the invoice and continue to collect from the customer (who may not know about it at all).
The difference in cost between the two is smaller than the fundamental difference in mechanism suggests, but both can easily run at more than 20% per annum, up to as much as 35% per year once annualised. That can be money well spent for a genuine cash-flow bridge, but a poor way to circumvent a collections process that can be fixed for free is a fine distinction to make before signing up.
The biggest misconception is that factoring damages customer relationships. In industries where it's normal: staffing, freight, manufacturing your customer's AP team processes factored invoices every week and thinks nothing of it. Where it does cause problems is when a small customer who's never seen it before gets a notice from a company they've never heard of. That's a communication failure, not a factoring problem, and a phone call beforehand solves it.
Anu Gupta, CA, EA, B.Tech · LinkedInCore Definitions
Invoice financing and factoring are both ways for businesses to access cash tied up in unpaid invoices, without waiting 30, 60, or 90 days for customers to pay. They are often confused, but they work differently: factoring involves selling your invoices to a third party; invoice financing involves borrowing against them while you retain collection responsibility. Understanding the distinction matters because they have different costs, customer impacts, and suitability.
Invoice Financing (also called Invoice Discounting or Accounts Receivable Financing): You use outstanding invoices as collateral to borrow money from a lender. You retain responsibility for collecting payment from customers. When customers pay, you repay the lender plus fees. Your customer may not know you have financed the invoice.
Invoice Factoring: You sell your unpaid invoices to a factoring company (the 'factor') at a discount. The factor advances you 70 to 90% of the invoice value immediately. The factor then collects payment directly from your customer. Once the customer pays the factor, the factor remits the remaining balance to you, less their fee.
Side-by-Side Comparison
| Dimension | Invoice Financing | Invoice Factoring |
|---|---|---|
| Mechanism | Loan secured by invoices, you borrow against them | Sale of invoices, you sell them at a discount |
| Who Collects from Customers | You, your customer never knows | The factor collects directly from your customer |
| Customer Awareness | Confidential, customer doesn't know | Customer is notified to pay the factor |
| Advance Rate | Typically 70 to 90% of invoice value | Typically 70 to 90% of invoice value |
| Fee Structure | Interest on amount borrowed: ~1 to 3% per month | Factoring fee: typically 1 to 5% of invoice face value |
| Credit Risk | You retain credit risk, if customer doesn't pay, you still owe the lender | Recourse factoring: you bear risk if customer doesn't pay. Non-recourse: factor bears the risk (higher cost) |
| Best For | Businesses that want confidentiality and have strong collections processes | Businesses that need outsourced collections or have less capacity to chase receivables |
| Speed | Typically 24 to 48 hours to set up and fund | Typically 24 to 72 hours to first advance |
| Contract Length | Usually flexible, per-invoice or facility | Often requires volume commitments or minimum periods |
Cost Comparison
Example: $100,000 invoice, 60-day payment term
| Invoice Financing | Invoice Factoring (Recourse) | |
|---|---|---|
| Advance | $85,000 (85%) | $85,000 (85%) |
| Fee (2 months) | ~$1,700 (2% × 2 months on $85K borrowed) | ~$3,000 to $5,000 (3 to 5% factoring fee on $100K) |
| Total Cost (annualised) | ~24% APR | ~18 to 30% APR depending on fee and term |
| You Receive Total | $100,000 − $1,700 = $98,300 (keep $13,300 reserve) | $85,000 advance + ~$10,000 to $12,000 reserve (less factor fee) |
| Who Collects | You chase the customer | Factor chases the customer |
NOTE: Factoring fees vary widely, always calculate the annualised rate equivalent. A 2% factoring fee on a 30-day invoice equals 24% APR. A 5% fee on a 90-day invoice equals 20% APR. Compare on this basis.
When to Use Each
| Invoice Financing is better if… | Invoice Factoring is better if… |
|---|---|
| You want to keep customer relationships fully intact, no third-party contact | You want to outsource collections entirely and free staff time |
| You have a strong internal collections process | Your customers have long payment terms (60 to 90+ days) and you cannot wait |
| Confidentiality is important (e.g. large enterprise customers) | You are growing fast and need predictable cash flow without a collections overhead |
| You want lower fees (financing fees are typically cheaper) | Your team lacks capacity to manage receivables, the factor handles it |
| You want flexibility per invoice, no volume commitment | You want credit protection (non-recourse factoring protects against customer insolvency) |
Before you finance anything
Both instruments cost 20%+ annualised. Worth confirming your cash gap is structural rather than self-inflicted, because the fixes below are free.
Are invoices going out the day work completes? A week's delay adds a week to every collection, permanently.
Does anyone follow up before the due date? A reminder five days before due does more than three chasers afterward.
What's your DSO against your stated terms? Net 30 collecting in 55 is a process problem. Net 60 collecting in 63 is structural, and that's what these instruments are for.
Have you asked customers for shorter terms? Smaller customers often accept Net 15 or a deposit if it's raised at the start of the relationship.
If your DSO sits well beyond your terms, fix that first. the detail is in our guide to accounts receivable challenges. If your terms themselves are the problem, financing is a reasonable answer.
Which to use Invoice financing or factoring
Invoice financing if you want customers kept out of it, your collections process is solid, confidentiality matters particularly with enterprise customers, you want to finance selectively rather than commit volume, or you want cost tied to how long the money is actually out.
Factoring if you want collections off your plate, your team lacks capacity to chase, your customers are on long terms, or you want non-recourse protection against a customer becoming insolvent.
On non-recourse specifically: it transfers insolvency risk, not dispute risk. A customer who says the work was incomplete isn't insolvent, they're disputing, and that usually comes back to you regardless. Read the precise definition of the credit event before paying the premium.
Our B2B customers were paying on 60 to 90 day terms, but our suppliers expected payment within 30 days, which left us with a serious cash gap during a period of rapid growth. Profitjets helped us arrange a $150,000 short-term working-capital facility that cost us about $4,500 in interest and fees over the period we used it. That was far less than the estimated $18,000 in lost discounts, late-payment costs, and delayed orders we would have faced if we hadn't covered the gap.
Book a free consultation and we will look at the cheaper fix first.
Frequently Asked Questions
Does factoring damage customer relationships?
Less than people fear, and it depends on the customer. In staffing, freight and manufacturing, factored invoices are routine and AP teams process them without comment. Smaller customers unfamiliar with it can react badly to an unexpected notice from a company they don't recognise. Call your significant customers before the factor's notice arrives, and ask whether the factor offers white-label collections.
What's the difference between recourse and non-recourse
With recourse, an unpaid invoice comes back to you the factor puts it back after a defined period, often around 90 days. Non-recourse means the factor absorbs the loss if your customer becomes insolvent, for a higher fee. What it generally doesn't cover is a disputed invoice, which is how most non-payment begins, so check the wording rather than the label.
Which is cheaper invoice financing or factoring?
Depends on your customers'payment behaviour. Financing charges for the days you're actually borrowing, so fast-paying customers cost you less. Factoring often charges a flat fee whichever way. If your customers pay reliably near the due date, financing usually wins; if they run long, a flat factoring fee may work out better.
Can I use these selectively, on some invoices only?
Financing facilities are frequently flexible that way. Factoring more often comes with minimum volume commitments and charges if you don't meet them. Spot factoring exists at a higher rate. Ask specifically about minimums before signing, it's a common source of unexpected cost.
How does this appear in my accounts?
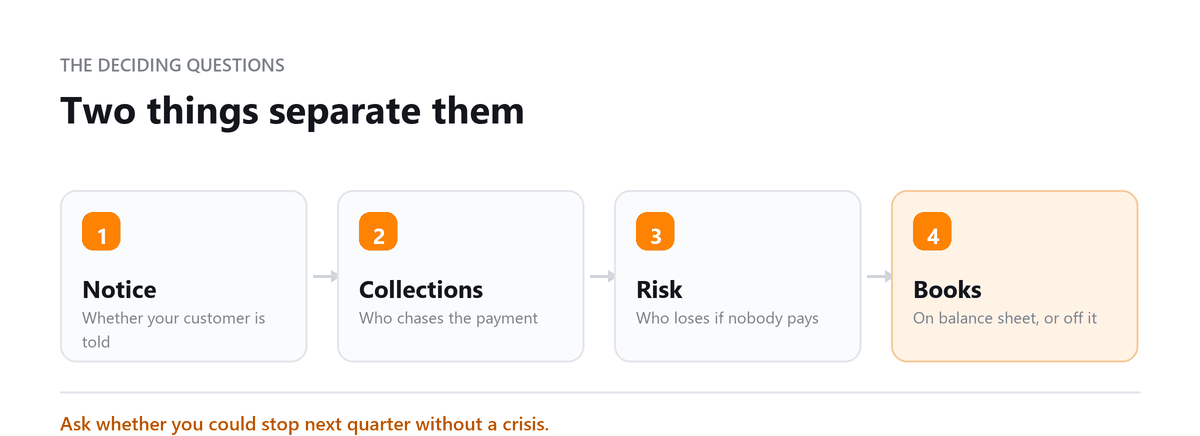
Financing is debt on your balance sheet. Factoring is often structured as a sale of an asset and may sit off it, though whether a specific arrangement qualifies as a true sale depends on its terms, recourse arrangements frequently don't. Have your accountant review the agreement before assuming the treatment.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Cash Tied Up in Invoices?
Book a free consultation and we will look at the cheaper fix first.