
Most discussions of S-Corp vs C-Corp boil down to either one of two questions.
If you are a successful owner operated business, considering converting your proprietorship to an S-Corp, you are asking yourself, will changing my business structure reduce my tax liability? It certainly can, and probably by less than you think, because the costs associated with the conversion are rarely taken into account in the discussions about the benefits.
If you are starting a new company and have an idea who your investors will be, you are asking yourself, what structure will they accept? In this case the answer is simple, a C-Corporation, because venture funds tend to purchase preferred stock and an S-Corp cannot issue any stock.
The similarities between these two cases end there, and this article will only discuss the math involved in the first scenario and the limitations of the second.
The election makes sense once profit is comfortably into six figures below that, the payroll processing, the separate corporate return and the higher accountant fees eat most of what you save. The figures you'll see quoting a $40,000 or $50,000 threshold are counting the tax saving and not the costs. And the saving is on the distribution portion only, up to the Social Security wage base above that the rate you're avoiding is 2.9%, not 15.3%, which changes the picture considerably at higher profit levels.
Anu Gupta, CA, EA, B.Tech · LinkedInCore Definitions
S-Corporations and C-Corporations are both incorporated business entities, but they differ fundamentally in how they are taxed and who can own them. Choosing the right structure affects your tax bill, your ability to raise capital, and your long-term exit options. This guide explains both structures, compares them side by side, and helps you determine which is right for your situation.
- C-Corporation: The default corporate structure. All corporations start as C-Corps. Subject to corporate income tax at 21% federal rate. Profits distributed as dividends are taxed again at the shareholder level (double taxation). Preferred by venture-backed startups and any business planning to go public.
- S-Corporation: A tax election (not a separate legal structure) that allows a corporation to be treated as a pass-through entity. The corporation files Form 2553 to elect S-Corp status. Profits and losses flow through to shareholders' personal returns, no corporate-level income tax. Subject to restrictions on who can be a shareholder.
S-Corp vs C-Corp: Head-to-Head Comparison
| Dimension | S-Corporation | C-Corporation |
|---|---|---|
| Tax Treatment | Pass-through, no corporate income tax; income taxed on shareholders' personal returns | Double taxation, 21% federal corporate tax; dividends taxed again at shareholder level |
| Shareholder Limit | Maximum 100 shareholders | Unlimited shareholders |
| Eligible Shareholders | US citizens and permanent residents only, trusts and estates permitted under rules | Anyone, individuals, corporations, foreign investors, trusts, funds |
| Stock Classes | One class of stock only, no preferred shares | Multiple stock classes permitted (common + preferred) |
| VC Investment | VCs cannot invest, they require preferred stock (not available in S-Corps) | VC-compatible, preferred stock is the standard investment instrument |
| Self-Employment Tax | Owner-employees pay SE tax only on their 'reasonable salary'; distributions above salary are not subject to SE tax | No self-employment tax consideration, corporate wages subject to payroll tax; dividends taxed at dividend rates |
| Corporate Tax Rate | No corporate income tax (pass-through) | 21% federal; state rates vary (0 to 12%) |
| Audit Risk | Lower than C-Corp (no corporate return separate from shareholders) | Standard corporate audit risk |
| IRS Scrutiny | 'Reasonable salary' rule, IRS scrutinises whether owner-employees are underpaying salary to avoid payroll tax | Standard corporate compliance scrutiny |
The S-Corp Tax Advantage: How It Works
A profitable single-owner business with $300,000 of net profit.
Without the election, self-employment tax applies to 92.35% of profit, $277,050. Of that, 15.3% applies up to the Social Security wage base and 2.9% applies above it, plus the 0.9% Additional Medicare surcharge over the threshold.
With the election, payroll tax applies only to the salary you take. Set a defensible salary at $120,000 and the remaining $180,000 comes out as distributions, free of SE tax.
Example: A profitable small business LLC with $300,000 in annual profit, one owner-operator.
| Scenario | Taxable Income | Self-Employment/Payroll Tax | Total Federal Tax Load |
|---|---|---|---|
| Sole Prop / Single-Member LLC | $300,000 all subject to SE tax | $300,000 × 15.3% (up to SS wage base) = ~$42,000 SE tax | $42,000 SE + income tax (~$76,000) = ~$118,000 |
| S-Corp Election | $120,000 'reasonable salary' + $180,000 distribution | Payroll tax on $120,000 salary only = ~$18,400 | ~$18,400 payroll + income tax (~$76,000) = ~$94,400 |
| Estimated Annual Savings via S-Corp Election | ~$23,600 SE/payroll tax saved |
NOTE: Savings depend on actual salary, distribution amounts, state, and tax year. S-Corp involves additional costs: payroll processing, separate corporate tax return (Form 1120-S), and quarterly payroll tax deposits. Net benefit is typically positive above ~$50,000 to $80,000 in annual profit, verify with your CPA.
Which Should You Choose?
| Choose S-Corp if… | Choose C-Corp if… |
|---|---|
| You are a profitable small business and want to reduce self-employment tax | You plan to raise venture capital (VCs require preferred stock, not available in S-Corps) |
| All your owners are US citizens or permanent residents | You have or expect international or institutional investors |
| You have 100 or fewer shareholders | You plan to go public (IPO requires C-Corp) |
| You do not need multiple stock classes for investors | You want to offer ISOs (Incentive Stock Options) with standard VC-style vesting |
| You want pass-through taxation without LLC complexity | You expect to retain profits in the company at the 21% corporate rate (may be lower than personal rate) |
What the election costs
The part missing from most advice, and the reason the threshold is higher than you'll read elsewhere.
Payroll, running all year. You become an employee of your own company. Processing, deposits, quarterly filings, a W-2 at year-end.
A separate corporate return. Form 1120-S, on top of your personal return, with K-1s.
Higher accountant fees. Two returns and a payroll function rather than one Schedule C.
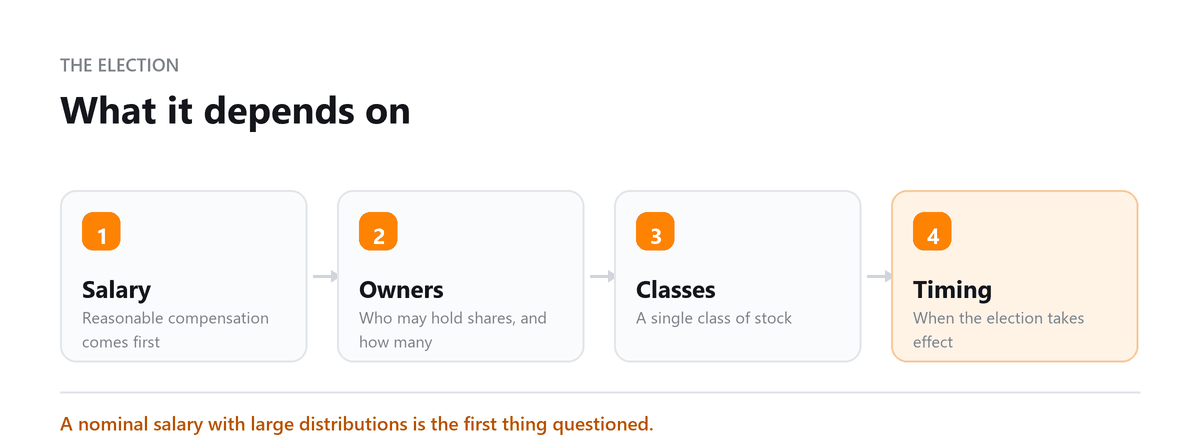
Reasonable salary documentation. The standard is real and the IRS examines S-Corps where salary looks artificially low. Getting it defended costs more than getting it right.
Less flexibility. Distributions must follow ownership proportionally, you can't allocate profits differently between owners the way an LLC can.
Realistically a few thousand dollars a year in added cost and administration. Against a saving that's meaningful at some profit levels and marginal at others, which is why the honest threshold sits in the low six figures rather than at $50,000.
Why to choose S-Corp vs C-Corp
S-Corp if you're a profitable owner-operated business, all shareholders are US persons, you have a hundred or fewer of them, you don't need multiple stock classes, and your profit is high enough that the saving clears the costs.
C-Corp if you're raising venture capital, you have or expect foreign or institutional investors, you're heading for an IPO, you want a standard employee option plan, you plan to retain earnings at the corporate rate, or a potential exit makes QSBS worth preserving.
On that last point: Section 1202 qualified small business stock can exclude a substantial portion of gain on a sale of C-Corp stock held long enough, and S-Corp stock never qualifies. For a founder building toward a sale, that can outweigh years of self-employment tax savings.
Book a free consultation and we will run the numbers before you file.
Frequently Asked Questions
Can an LLC elect S-Corp status?
Yes, and it's the most common route. The LLC files Form 2553 and is taxed as an S-Corporation while remaining an LLC legally same operating agreement, same state filings. You get the self-employment tax treatment without converting the legal structure.
What counts as a reasonable salary?
What you'd pay someone else to do your job, based on your role, hours, experience and industry. There's no safe percentage, despite the rules of thumb circulating online. The IRS examines S-Corps where salary looks suppressed relative to distributions, and losing that argument means back payroll tax and penalties. Document how you arrived at the figure, and have your accountant review it annually.
When does the election actually pay?
Once the self-employment tax saved exceeds the payroll processing, extra filing and accounting costs generally in the low six figures of profit, not at $40,000 or $50,000. The saving also concentrates below the Social Security wage base, so it doesn't grow proportionally as profit rises. Model it with your accountant against your own numbers.
What are the deadlines for electing?
Form 2553 has timing rules relative to the tax year you want it effective for, with late election relief available in some circumstances. Miss the window and you generally wait a year. Have the conversation before the filing season rather than during it.
I'm not a US citizen. Can I use an S-Corp?
No. S-Corp status requires US citizens or permanent residents as shareholders, and a non-qualifying shareholder invalidates the election, the company then defaults to C-Corporation taxation, which is neither of the outcomes you intended. If a US advisor suggests it, tell them your residency status first.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Considering an S Election?
Book a free consultation and we will run the numbers before you file.