
A small business does not fail because of fraud schemes, low-quality products or services, or a lack of customer service. Usually, the reason is a lack of control and visibility of the owner of the company’s finances.
In particular, personal and business expenses often overlap, confusing the owner about the money flow. The accounts are usually cluttered at the end of the year when it is time to prepare the tax return. The cash on hand is mistaken for profit, while some customers still owe money.
These issues are rarely urgent, and owners and managers do not realize that their small business is in trouble immediately. A few symptoms, however, may appear: one line item that was expensed on the tax return; the bank loan that turned out to be problematic because the financial statements were misleading; an unnecessary hire that the company could not afford in the long run. However, the damage is already being done when they become apparent.
The best part about formulating an actionable fiscal strategy is that it is relatively simple and straightforward in theory. It is also imperative to implement it step by step without skipping a vital stage.
The distinction of personal and business expenses, the protection of the owner’s credit, the monthly review of the financial statements and setting up a realistic budget are just a few things that will bring order. After that, the company will have a realistic understanding of its financial condition at any time.
This guide explains why financial organization matters and walks through five steps to take your business finances from scattered to fully under control.
Why Is Financial Organisation Important?
- Cash visibility: knowing your true cash position, what is owed to you, and what you owe others is the baseline for every financial decision
- Tax compliance: disorganised finances mean missed deductions, inaccurate returns, and penalties. Organised finances make tax preparation faster and cheaper
- Lender/investor confidence: any bank loan, line of credit, or equity investor will require accurate financial statements. Disorganised books disqualify you from financing you may need
- Business valuation: when you sell the business, buyers pay for clean, auditable financial history. Disorganised books reduce sale price and extend deal timelines
- Decision quality: business decisions made with accurate financial data produce better outcomes than decisions made on gut feel or incomplete information
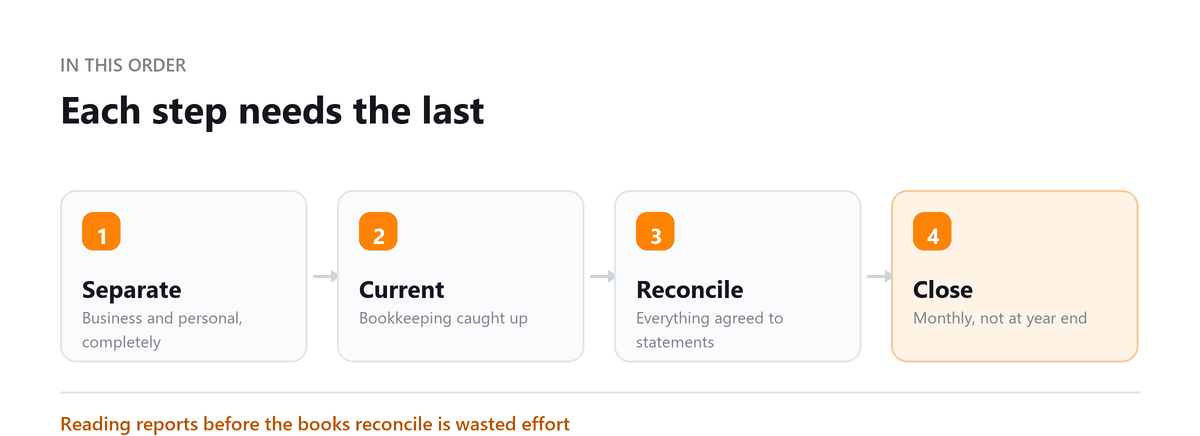
Step 1: Separate Personal and Business Finances
If you're running business transactions through personal accounts, stop now. Open a dedicated business checking account and a business credit card, and use them for business activity only.
Then deal with the past. Any personal money you've put into the business should be recorded either as a capital contribution, meaning an owner investment, or as a loan from the owner. If the amount is significant and you treat it as a loan, document it with a simple promissory note.
This one step makes every other part of this guide easier. It also protects your deductions and, for LLCs and corporations, helps preserve the legal separation between you and the business.
Step 2: Monitor and Build Your Business Credit
Your business credit profile affects the terms suppliers and lenders offer you. A strong profile can mean better financing terms, higher credit limits, and smaller deposits. The main business credit bureaus are Dun & Bradstreet, Experian, and Equifax.
Building business credit takes a few consistent habits. Get a DUNS number from Dun & Bradstreet. Open a business credit card, even a secured one if you're just starting out. Work with suppliers who report payments to the business credit bureaus, and pay them on time or early. Then check your business credit files periodically to make sure the information is accurate.
When a new client's finances are a complete mess, the first thing I do isn't open the accounting software. It's get every bank and credit card statement for the past 12 months in one place. Once you reconcile the actual money that moved, the true picture shows up fast: what was business, what was personal, what's missing from the books. That single step gives more clarity in a week than months of guessing from a half-updated ledger.
Ankit Sagatani, MBA, B.Com · LinkedInStep 3: Implement Strong Financial Reporting
You need three financial statements, produced accurately, every month:
| Statement | What It Shows | Key Questions It Answers |
|---|---|---|
| Profit & Loss (Income Statement) | Revenue, expenses, and net profit for the period | Am I profitable? Which costs are growing? Is margin improving? |
| Balance Sheet | Assets, liabilities, and equity at a point in time | What does the business own? What does it owe? What is it worth? |
| Cash Flow Statement | Cash inflows and outflows by category | Where is cash coming from? Where is it going? Is operating cash positive? |
All three statements should be ready within 5-7 business days of month-end. If it takes longer, the accounting process is too slow and should be restructured.
Step 4: Build a Clear Budget
Once you have three to six months of clean, reliable financial history, you're ready to build a 12-month budget.
Forecast revenue by segment rather than as one number. List your fixed costs by category, estimate variable costs as a percentage of revenue, and project net profit month by month.
Then compare actual results against the budget every month. A budget isn't a prediction you're expected to hit exactly. It's a benchmark that makes it obvious when revenue is running behind or costs are creeping up, so you can respond while there's still time.
Step 5: Put Strong Payables and Receivables Processes in Place
Accounts Payable: What You Owe
Send every bill to one place so nothing gets lost in someone's inbox. For purchases of goods, match the purchase order, receiving record, and invoice before paying. For services, confirm with the person who requested the work that it was delivered. Set clear approval limits so larger payments need sign-off.
Pay within the agreed terms. There's usually no benefit to paying early unless the supplier offers a discount for it. Reconcile your payables and supplier statements every month.
Accounts Receivable: What Customers Owe You
Send invoices as soon as work is delivered, not at the end of the month. Set clear payment terms up front and automate reminders before the due date and at regular intervals after it.
Review your receivables aging report every week and follow up personally on anything more than 30 days overdue. The longer an invoice sits unpaid, the less likely it is to be collected.
How Profitjets Helps
Profitjets provides outsourced bookkeeping, accounting, and fractional CFO services that put all of these systems in place for small businesses, without the cost of building an in-house finance team.
That includes cleaning up historical records, separating business and personal activity, closing the books every month, producing your three core financial statements, building a budget, and tightening your payables and receivables processes.
If your books are behind or your finances feel scattered, the first step is a review of where things stand today.
An initial conversation with Profitjets usually covers your accounts and software, how far behind the books are, and what you need most, whether that's catch-up bookkeeping, monthly reporting, tax readiness, or financial planning. From there, you'll get a clear plan and timeline to bring everything up to date.
Book a free consultation and we will catch you up.
Frequently Asked Questions
How long does it take to get business finances organized?
It depends on where you're starting. If you have 12 months or more of mixed personal and business transactions and no real accounting system, rebuilding accurate records usually takes four to eight weeks. If there's some structure but the records are incomplete, it's often two to four weeks. After that, a professional bookkeeper can typically close each month within five to seven business days.
What accounting software is best for a small business?
QuickBooks Online is the most widely used in the US and works with the largest network of accountants and connected apps. Xero is a strong alternative with a clean interface and good multi-currency support. Wave suits very small businesses with simple needs, and FreshBooks is popular with service businesses that bill by project. In practice, the best choice is often the one your bookkeeper or accountant already knows well.
Do I need a bookkeeper or an accountant?
Most businesses need both, for different reasons. A bookkeeper handles day-to-day transactions, reconciliations, and the month-end close. A CPA handles tax returns, year-end financial statements, and tax planning. Outsourced firms like Profitjets often provide both, so the bookkeeping and tax work sit with one team.
How do I fix years of mixed personal and business transactions?
Start by gathering every bank and credit card statement for the affected period. Go through each transaction and classify it as business or personal. Personal expenses paid by the business are usually recorded as owner draws, and business expenses paid personally as owner contributions. A bookkeeper can do this far faster and more accurately, especially when multiple years are involved.
What financial reports should a small business review every month?
At a minimum, review the profit and loss statement, balance sheet, and cash flow statement. It's also worth checking your accounts receivable aging, accounts payable aging, and a comparison of actual results against your budget. Together, these give you a full picture of profitability, cash, and anything that needs attention.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Months Behind on the Books?
Book a free consultation and we will catch you up.