
Understanding the difference between the W-4 vs W-2 is crucial for proper payroll processing. W-4 is a form indicating the amount of federal income tax to withhold from each paycheck, while W-2 is a record of wages and taxes for the year.
At Profitjets, during our monthly payroll audits, we discovered about 28% errors in W-4 elections filed by our clients, causing significant year-end liabilities discrepancies for both employees and employers.
The W-4 and W-2 are two of the most important US tax forms for employees and employers but they serve completely different purposes. The W-4 is completed by the employee when they start a job to tell their employer how much federal income tax to withhold from each paycheck. The W-2 is completed by the employer and sent to each employee by January 31, reporting the employee's total wages and all taxes withheld for the prior year. Understanding both forms is essential for correct payroll withholding and accurate tax filing.
The W-4 scenario that most commonly blindsides employees with an unexpected April tax bill is checking the Single/Married filing status without completing Step 2 for a dual-income household, an oversight that can be easily caught through a quick mid-year withholding check using the IRS Estimator tool.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is the W-4 Form?
Form W-4 (Employee's Withholding Certificate) is a form employees complete when starting a new job and update whenever their personal or financial situation changes in a way that affects their tax liability. The W-4 tells the employer how much federal income tax to withhold from each paycheck.
| W-4 Section | Purpose |
|---|---|
| Step 1, Personal information | Name, SSN, address, filing status (Single/MFJ/Head of Household) |
| Step 2, Multiple jobs / spouse works | Adjusts withholding if you have more than one job or your spouse works, prevents underwithholding |
| Step 3, Claim dependents | Reduces withholding by the Child Tax Credit and other dependent credits |
| Step 4, Other adjustments | Add other income (interest, dividends, side income) to increase withholding; add deductions to reduce withholding; add extra amount per paycheck |
| Step 5, Signature | Employee certifies the form under penalty of perjury |
When to Update a W-4
- You get married or divorced
- You have a baby or adopt a child
- You start a second job or your spouse starts/stops working
- You have a significant change in income from investments, freelance work, or rental income
- You owed a large tax bill last April and want more withheld
- You received a large refund and want to reduce withholding to increase take-home pay
Note: The IRS has a free Tax Withholding Estimator tool (irs.gov/W4app) that employees can use to check whether their current W-4 is calibrated correctly, especially useful after major life events or changes in income.
What is the W-2 Form?
Form W-2 (Wage and Tax Statement) is an employer-issued form that reports an employee's annual wages and all taxes withheld. Employers must send the W-2 to each employee by January 31 of the year following the tax year (e.g., January 31, 2026 for the 2025 tax year). A copy is simultaneously filed with the Social Security Administration (SSA) and with the applicable state.
| W-2 Box | What It Reports |
|---|---|
| Box 1 | Federal taxable wages (gross wages minus pre-tax deductions like 401k, HSA, Section 125 benefit premiums) |
| Box 2 | Federal income tax withheld |
| Box 3 | Social Security wages (may differ from Box 1 if pre-tax deductions are not SS-exempt) |
| Box 4 | Social Security tax withheld (6.2%) |
| Box 5 | Medicare wages (typically all wages; no cap) |
| Box 6 | Medicare tax withheld (1.45% + 0.9% additional Medicare if applicable) |
| Box 12 | Various codes, 401k contributions (D), health savings account (W), group term life (C), dependent care FSA (E) |
| Box 13 | Check if: statutory employee / retirement plan participant / third-party sick pay |
| Box 15 to 20 | State wages, state tax withheld, local wages, local tax withheld |
W-4 vs W-2: Key Differences
| Dimension | W-4 | W-2 |
|---|---|---|
| Purpose | Tells employer how much to withhold per paycheck | Reports annual wages and taxes withheld, used for annual tax return |
| Who completes it | Employee | Employer |
| When | At hire; updated as needed | At year-end; distributed by January 31 |
| Sent to IRS? | No, retained by employer | Yes, employer files Copy A with SSA/IRS by January 31 |
| Effect on taxes | Sets withholding amount per paycheck | Used by employee to complete Form 1040 annual return |
| Frequency | Once (updated as needed) | Once per year per employee |
| Penalty for non-compliance | Employee may owe underpayment penalty if withholding too low; employer must withhold at default rate if no W-4 on file | Employer faces IRS penalties for late or incorrect W-2 to $60 to $320 per form depending on timing |
Common W-4 and W-2 Mistakes
| Mistake | Consequence | Fix |
|---|---|---|
| Employee claims too many allowances on W-4 / significantly under-withholds | Owes large tax bill in April; may owe underpayment penalty | Use IRS Tax Withholding Estimator; update W-4; consider requesting extra withholding in Step 4(c) |
| Employer does not update employee records when W-4 changes submitted | Wrong withholding continues; employee liable for underpayment | Process W-4 changes within the first payroll run after receiving the updated form |
| Employer sends W-2 after January 31 deadline | IRS penalty of $60 to $320 per W-2 depending on timing; employee may be unable to file return on time | Use payroll software that automatically generates and distributes W-2s; set a hard internal deadline of January 20 for final payroll reconciliation |
| W-2 Box 1 wages do not match payroll records | Triggers IRS CP2000 match notice to employee; potential audit | Reconcile W-2 Box 1 to payroll register and 941 filings before distribution, all three figures should agree (within pre-tax deduction adjustments) |
By implementing automated mid-year W-4 tax withholding reviews, Profitjets enables client organizations to eliminate over 90% of end of year W-2c corrective filings and avoid IRS late-furnishing penalties.
During a recent year-end payroll reconciliation for an IT services client, we uncovered a $42,000 variance between their quarterly Form 941 filings and total W-2 Box 1 figures across 35 employees.
The discrepancy stemmed from an uncalibrated payroll tool that failed to properly exclude pre-tax 401(k) contributions from federal taxable wage buckets, causing improper tax reporting. Our team immediately recalculated the wage bases, filed corrected Form W-2c returns with the Social Security Administration, and re-aligned their payroll software to ensure future W-4 changes auto-flow accurately into annual tax summaries.
FAQs
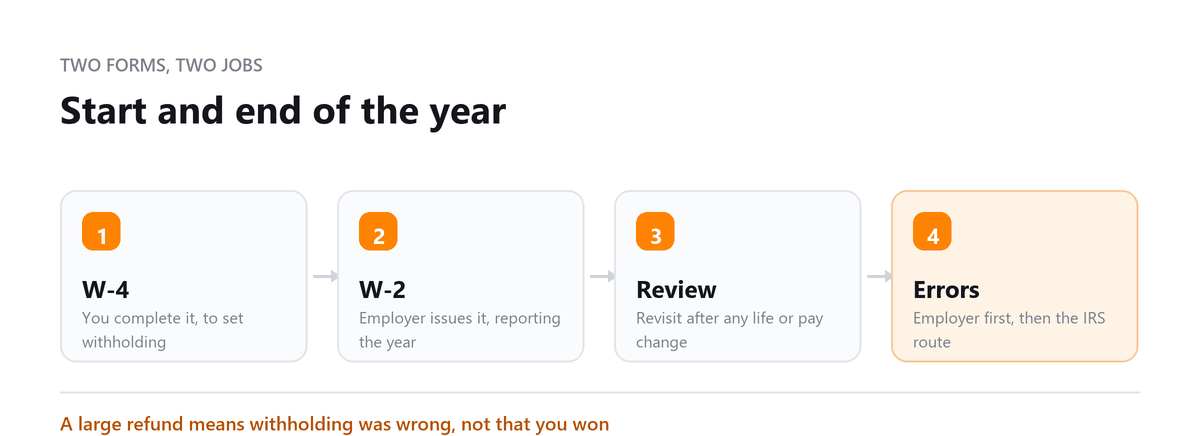
When to Revisit Your W-4
Most people complete the form once when they join and never look at it again, which is how withholding drifts away from what is actually owed.
- A second job, or a household where both people work
- A marriage, a divorce, or a change in who you can claim
- Significant income outside employment, whether self-employment, investments or rental
- A large refund or a large balance due on your last return, both of which mean withholding is off
- A pay change large enough to move you between brackets
A refund is not a win. It means more was withheld through the year than was owed, and the money was unavailable to you in the meantime. A large balance due is worse, since it can bring an underpayment charge on top. The IRS publishes a withholding estimator that is the right tool for checking, and mid-year is a better time to run it than January.
What to Check on a W-2 Before Filing
The form arrives, gets attached to a return and is rarely read. A few minutes of checking prevents the most common notices.
Confirm your name and identifying number are exactly right, since a mismatch delays processing. Compare the wages shown against your final payslip for the year, remembering that taxable wages differ from gross pay where pre-tax deductions exist, so the boxes are not expected to agree with each other. Check the state information if you worked in more than one state, and check that retirement and benefit amounts look right.
If you had more than one employer during the year, make sure you have a form from each. A missing one is the most frequent cause of a notice months later, because the income was reported to the IRS whether or not it reached your return.
If a Form Is Wrong or Missing
Neither situation is unusual and both have a defined route, which is worth knowing before a deadline.
Start with the employer, since a corrected form issued by them is the cleanest outcome. Keep a record of when you asked and what you were told. Where an employer cannot or will not act, the IRS has a documented process for missing or incorrect forms that allows a return to be filed on the best information available, typically the final payslip.
Do not simply file with figures you have adjusted yourself and no explanation. The reported and filed figures will not match, and the resulting correspondence is slower to resolve than following the process. Check the current IRS guidance for the steps and the point in the year at which each applies.
Book a free consultation and we will run payroll properly for you.
FAQs
Do I need to submit a new W-4 every year?
No. Your Form W-4 generally remains in effect until you submit a new one. However, you should consider updating it when your tax situation changes significantly, such as after marriage, divorce, having a child, starting a second job, or experiencing a major change in income. The IRS Tax Withholding Estimator can help you determine whether your current withholding is appropriate.
What if I don't receive my W-2 by January 31?
Contact your employer first because employers generally must furnish Form W-2 by January 31. If you still have not received it by the middle of February, you can contact the IRS for assistance. If necessary, you may use Form 4852, Substitute for Form W-2, to file your tax return using your best estimate of wages and withholding.
What is the difference between Form W-4 and Form W-2?
Form W-4 tells your employer how much federal income tax to withhold from your paycheck. Form W-2 reports your annual wages and the taxes withheld during the year and is used when preparing your federal and state income tax returns.
When should I update my Form W-4?
You should review your W-4 whenever there is a significant change in your personal or financial circumstances. Changes in marital status, dependents, multiple jobs, self-employment income, or significant changes in deductions or credits can affect how much tax should be withheld from your paycheck.
Can I change my W-4 more than once during the year?
Yes. You can submit a new W-4 to your employer whenever you need to adjust your federal income tax withholding. Your employer generally uses the updated information for future pay periods, subject to its payroll processing schedule.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Payroll Forms Causing Confusion?
Book a free consultation and we will run payroll properly for you.