
What Is an Accounting Period?
An accounting period is the defined timeframe during which a business tracks, aggregates, and reports its financial activity. Every journal entry, invoice, expense, and bank transaction is assigned to a specific accounting period, and at the end of that period, financial statements are prepared to summarise what happened. Accounting periods can range from a single week to a full fiscal year, depending on the business's reporting needs and regulatory requirements.
The concept of the accounting period is fundamental to the matching principle, one of the core tenets of accrual accounting. Revenue and expenses are recognised in the period they occur, not necessarily when cash changes hands. This produces financial statements that accurately reflect the economic activity of each period, making it possible to compare performance consistently over time.
The choice of accounting period matters more than most business owners realise, especially for seasonally variable businesses. A retailer using a calendar year compares their strongest quarter (Q4) against their weakest (Q1) without any structural adjustment. A well-chosen fiscal year can give you much cleaner period-on-period comparisons.
Ankit Sarawagi, CPA, CA, MBA · LinkedInThe Accounting Period Cycle
Each accounting period follows the same predictable cycle: the period opens with beginning balances carried forward from the prior period. Throughout the period, transactions are recorded as journal entries in the appropriate accounts. At period end, adjusting entries are posted to capture accruals (revenues earned but not yet billed, expenses incurred but not yet paid), deferrals (cash received or paid in advance), and depreciation. Financial statements, income statement, balance sheet, cash flow statement, are then prepared.
Finally, temporary accounts (revenues and expenses) are closed to retained earnings, resetting them to zero for the next period. Then the cycle repeats.
Types of Accounting Periods
Calendar Year
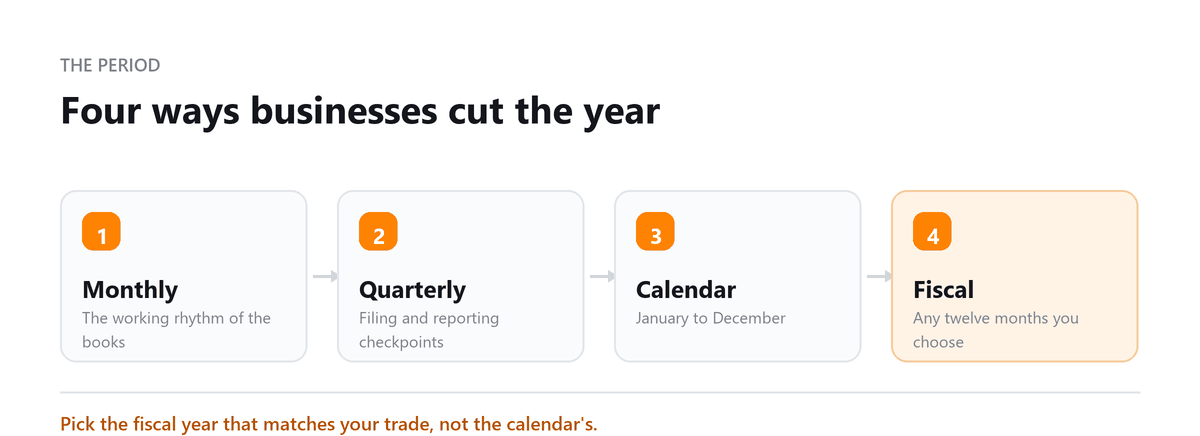
The calendar year accounting period runs from January 1 to December 31. It is the most common choice for small businesses because it aligns naturally with personal income tax filing, simplifies year-end planning, and is easily understood by all stakeholders. Banks, investors, and the IRS all operate on a calendar year by default. Businesses with relatively stable revenue throughout the year benefit most from this structure.
Fiscal Year
A fiscal year is any 12-month accounting period that ends on a date other than December 31. Large corporations and government entities frequently use fiscal years that better align with their natural business cycle. Retailers, for example, often end their fiscal year in January, after the holiday season rush, so their strongest quarter is not split across two reporting years. Apple's fiscal year ends in late September. The U.S. federal government's fiscal year runs October 1 to September 30.
Any fiscal year end is permissible as long as it ends on the last day of a month.
4-4-5 / 4-5-4 / 5-4-4 Calendar
Retail and consumer-facing businesses often use week-based accounting calendars that group weeks into months in structured patterns, 4 weeks, 4 weeks, 5 weeks (4-4-5); or 4 weeks, 5 weeks, 4 weeks (4-5-4); or 5 weeks, 4 weeks, 4 weeks (5-4-4). This approach ensures that each quarter contains exactly the same number of weeks and that same-day-of-week comparisons are possible across periods. The trade-off is that the annual period may not end on December 31.
Calendar Quarter
Calendar quarters divide the calendar year into four equal three-month segments: Q1 (January, March), Q2 (April, June), Q3 (July, September), and Q4 (October, December). Calendar quarters are used for quarterly estimated tax payments (Form 1040-ES), quarterly investor reporting for public companies, and many lender covenants. Most small businesses track financial performance at least at the quarterly level.
Fiscal Quarter
Fiscal quarters are the four three-month segments within a non-calendar fiscal year. A business with a fiscal year ending September 30 would have fiscal Q1 running October, December, Q2 January, March, Q3 April, June, and Q4 July, September. Fiscal quarters align with the company's operational rhythm rather than the calendar, and are the basis for public company quarterly earnings reports (10-Q filings) when using a non-calendar fiscal year.
Calendar Month
The calendar month is the most common internal reporting period for businesses of all sizes. Monthly closes, completing all transactions, reconciling accounts, and preparing financial statements, give management timely visibility into performance roughly every 30 days. Monthly reports allow early detection of cost overruns, revenue shortfalls, or cash flow problems before they compound into larger issues.
Fiscal Month
A fiscal month is a month within a non-calendar fiscal year structure. For companies using week-based retail calendars (4-4-5 etc.), fiscal months contain a fixed number of weeks rather than calendar days, which enables more consistent period-on-period comparisons. The length of a fiscal month may vary from 28 to 35 days depending on the calendar structure used.
Why the Accounting Period Matters for Your Business
Consistent accounting periods are the foundation of comparable financial reporting. Without them, performance trends are difficult to assess, audits become more complex, and lender or investor reporting becomes error-prone. A well-chosen accounting period also supports accrual accounting compliance, aligns tax filings with operational realities, and enables meaningful benchmarking against prior periods and industry peers. Changing your accounting period after establishing one requires IRS approval, choosing wisely from the start avoids that complexity.
Best Practices for Setting Accounting Periods in 2026
Align your accounting period with your operational cycle. If your business has a clear seasonal peak, holiday retail, summer tourism, back-to-school, structure your fiscal year so the peak falls within a single period, making comparison cleaner. Retailers often benefit from a 4-4-5 calendar that provides consistent week counts across periods.
Automate journal entries wherever possible. Modern accounting software can schedule recurring accruals, depreciation entries, and prepaid amortisation to post automatically at period end, significantly reducing manual workload during the close process. The less manual effort required, the faster and more accurate your closes will be.
Synchronise accounting periods across all business systems. Your payroll system, invoicing platform, inventory management software, and accounting ledger should all operate on the same period structure. Misalignment creates reconciliation headaches at every close and increases the risk of transactions falling into the wrong period.
Coordinate with your tax professional before adopting a non-calendar fiscal year or considering a change. Changing your tax year requires filing IRS Form 1128 (Application to Adopt, Change, or Retain a Tax Year) and typically results in a short tax year return for the transition period. The process carries tax implications and administrative cost, expert guidance is essential.
How Outsourced Accounting Fits In
For many small and mid-size businesses, managing the period-close process internally, completing adjusting entries, reconciling all accounts, preparing financial statements, and packaging reports for management review, is time-consuming and error-prone without dedicated accounting staff. Outsourced bookkeeping and accounting providers like Profitjets manage the period-close process end-to-end: posting accruals and deferrals, reconciling bank and credit card accounts, and delivering clean, timely financial statements after each period. This frees business owners and management from the administrative burden while ensuring every period is closed correctly and on schedule.
Conclusion
An accounting period is more than an administrative choice, it shapes how you measure performance, file taxes, and communicate with stakeholders. Understanding the options available, calendar year, fiscal year, quarters, months, and retail-oriented week-based calendars, and matching them to your business's operational reality is a foundational financial decision. Get it right from the start, and every close, every report, and every comparison thereafter becomes more meaningful.
Book a free consultation and we will tell you which one suits your trade.
Frequently Asked Questions
Can I change my accounting period once I've established one?
Yes, but it requires IRS approval. You must file Form 1128 (Application to Adopt, Change, or Retain a Tax Year) and meet specific criteria. The change typically requires a short tax year return for the transition period. Consult a CPA before initiating the change.
What is the difference between a calendar year and a fiscal year?
A calendar year runs January 1 to December 31. A fiscal year is any 12-month period that ends on a date other than December 31, for example, April 1 to March 31. Businesses choose fiscal years that better align with their natural business cycle.
How does the accounting period affect my quarterly tax payments?
Estimated quarterly tax payments (Form 1040-ES for individuals, 1120-W for corporations) are due on set dates regardless of your fiscal year. Your accountant will map your fiscal quarters to the IRS payment schedule. Misalignment can create planning complexity, another reason many small businesses use the calendar year.
What happens at the end of an accounting period?
The period-close process includes completing all transactions, posting adjusting entries (accruals, deferrals, depreciation), reconciling accounts, preparing financial statements, and posting closing entries to zero out temporary accounts. This typically takes 3 to 10 business days after period end.
Do I need a different accounting period for tax purposes vs internal reporting?
You can run internal management reports on any schedule (monthly, weekly). However, your tax year determines when annual returns are filed. Most businesses align their internal reporting period with their tax year for simplicity, but some use calendar month reporting within a fiscal year structure.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Choosing a Year End?
Book a free consultation and we will tell you which one suits your trade.