
The income is high, the expenditures are low, and there is a hefty profit in December. Then, January is the opposite, where income is low, expenses are high, which results in lesser profits. There is no actual change in costs and income, except that the payroll of the last week of the year, the December’s electricity bill, and the accountant’s invoice for the year-end close all fall on January.
This is because accrual accounting practices dictate that expenses are charged when they are incurred to authorize for the period in which they were used, not when they are paid.
If the staff works the last five days of December, their wages should be accrued as a December expense even if they are paid on January 5th. Failure to record accrual entries results in inaccurate profits where some months report higher profits than they actually did while others report lower ones compared to the actual profits.
In any business that needs to generate financial statements to present to lenders, investors, or to aid internal decision-making, accrual accounting is essential.
This guide explains what accrued expenses are, common examples, how to record and track them, how they compare with accounts payable and accrued revenue, and the pros and cons of accrual accounting.
What Are Accrued Expenses?
An accrued expense is a liability, money the business owes for services already received or costs already incurred, even though no invoice has arrived and no payment has been made. Common examples: employee salaries earned by December 31 but paid on January 5; utility bills for December usage that arrive in January; interest on a loan that accrues daily but is paid monthly.
| Accrued Expense | Example |
|---|---|
| Salaries & wages | Staff worked the last 5 days of the month; payroll paid on the 5th, 5 days must be accrued at month-end |
| Utilities | December electricity used but billed in January, December cost accrued |
| Interest | Monthly interest accrues daily on a loan balance; must be accrued even if paid at month-end |
| Rent | Rent due on the 1st sometimes received/paid on the 28th prior, must match the period it covers |
| Professional fees | Lawyer/accountant work performed in Q4 but invoiced in Q1, Q4 cost must be accrued |
| Taxes | Income tax, payroll tax, and sales tax liabilities accrue based on transactions, payable on schedule |
The accrual small businesses miss most often is wages. Payroll runs a few days after month-end, so the last week of work never gets recorded in the month it was earned, and every month looks slightly more profitable than it really is. Professional fees are a close second, especially at year-end, when the CPA's and attorney's work for Q4 doesn't get billed until February. Individually they look small, but together they can move a year's profit by enough to matter to a lender.
Abhinav Gupta, CPA, CA, MBA · LinkedInImportance of Accruing Expenses
- Accurate financial statements: accrual accounting matches revenue and expenses to the period they relate to, the foundation of GAAP-compliant financials
- Reliable month-end close: consistent accruals allow month-to-month P&L comparisons without distortion from timing differences
- Correct tax reporting: businesses using accrual accounting for tax purposes must accrue expenses properly, misstated accruals affect taxable income
- Lender/investor confidence: audited financials require proper accruals; lenders and investors rely on the accuracy of reported profit and equity
How to Track Accrued Expenses on the Balance Sheet
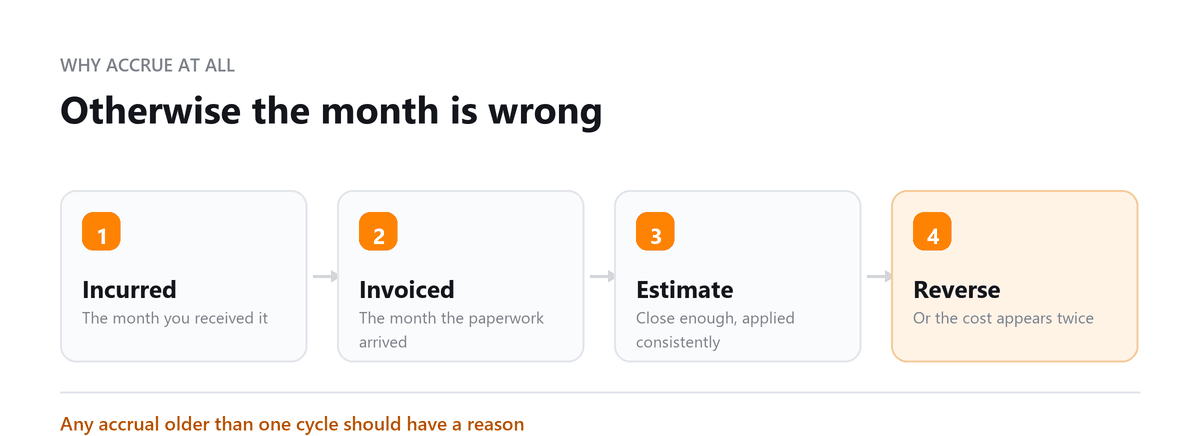
Accrued expenses appear as current liabilities on the balance sheet under 'Accrued liabilities' or 'Accrued expenses payable.' The entry to record an accrual: Debit the expense account (P&L) and Credit the accrued liability account (balance sheet). When the invoice arrives or payment is made: Debit the accrued liability and Credit cash (or accounts payable).
Balance sheet example from live page:
| Accrued Liability | Balance |
|---|---|
| Accrued salaries | $10,000 |
| Accrued utilities | $2,000 |
| Accrued interest | $1,500 |
| Accrued rent | $5,000 |
| Total accrued expenses | $18,500 |
Accrued Expenses vs Accounts Payable
| Accrued Expenses | Accounts Payable | |
|---|---|---|
| Invoice received? | No, expense incurred but not yet invoiced | Yes, invoice received and recorded |
| Basis | Expense recognised on accrual basis (time/usage) | Invoice-based (triggered by supplier invoice) |
| Balance sheet line | Accrued liabilities (current liability) | Accounts payable (current liability) |
| Example | December salaries payable January 5 | November supplier invoice due December 15 |
Accrued Expenses vs Accrued Revenue
Accrued expenses are costs incurred but not yet billed (a liability). Accrued revenue is income earned but not yet billed (an asset). Both arise from the matching principle in accrual accounting, recognising economic activity in the period it occurs, regardless of cash flow.
Pros and Cons of Accrual Accounting
| Pros | Cons |
|---|---|
| Accurate financial statements, matches revenue and expenses to the period they relate to | More complex than cash-basis accounting, requires month-end journal entries |
| Required for GAAP compliance, mandatory for businesses over $26M in gross receipts (IRS threshold) | Accruals require estimates, salaries, utilities, interest must be calculated before exact amounts are known |
| Better for financial analysis, enables reliable period-to-period comparisons | Can overstate profit short-term, expenses not yet paid may be accrued but cash has not left the business |
Accrued expenses keep your financial statements honest by recording costs in the period they were actually incurred, not whenever the bill turns up. The most common ones, including wages, utilities, interest, and professional fees, are easy to overlook and easy to fix with a short checklist at every month-end close. Record them consistently, clear them when the bills arrive, and your monthly results will reflect how the business really performed.
Frequently Asked Questions
Book a free consultation and we will get the accruals right.
Frequently Asked Questions
Are accrued expenses the same as prepaid expenses?
No, they're opposites. Accrued expenses are costs incurred but not yet paid or billed, and they're recorded as liabilities. Prepaid expenses are costs paid in advance, such as an annual insurance premium, and they're recorded as assets and expensed over the period they cover.
Does a cash-basis business need to track accrued expenses?
Not in its own books. Cash-basis accounting records expenses when they're paid, so accruals aren't recorded. However, larger businesses above the IRS gross receipts threshold, which is adjusted for inflation each year, generally must use the accrual method for tax purposes. And even smaller businesses often prepare accrual-basis statements for lenders or investors because they give a more accurate picture.
Are accrued expenses tax deductible?
Generally yes, for businesses using the accrual method, but the timing rules can be specific. Certain accrued expenses, such as some bonuses or amounts owed to related parties, may only be deductible when paid or within a set period after year-end. Your CPA can confirm how your year-end accruals should be treated.
How often should accrued expenses be recorded?
At the end of every month as part of the month-end close. Recording them only at year-end means your monthly reports will overstate or understate profit throughout the year.
What happens if the actual bill is different from the accrued amount?
It's normal for estimates to be slightly off. When the actual bill arrives, the difference is recorded as an adjustment to the expense in that period. If your estimates are consistently far off, it's worth refining how you calculate them.

Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Monthly Numbers Jumping About?
Book a free consultation and we will get the accruals right.