Business owners know approximately what they owe. They know the amount owed on their credit line, the equipment loan, and the stack of bills from suppliers due this month.
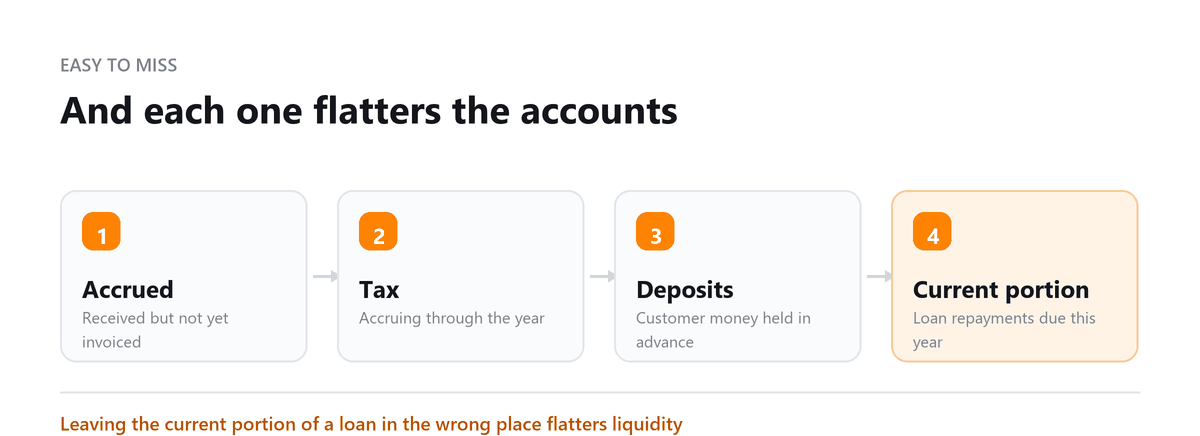
What they may not realize are the obligations that are not easily seen, such as payroll that has been earned but not yet paid, sales tax collected but not yet sent to the state, a customer deposit for work not yet begun, or the principal repayment due on a five year loan for the next twelve months.
Each of these is a liability, and altogether they imply information not obvious from the bank balance. Taken together, liabilities suggests the percentage of cash tied up in obligations, and the percentage of the business funded by others, and the risk to the business if cash flow decreases for an extended period of time. Lenders consider liabilities, often before looking at profit and loss.
The importance of knowing liabilities goes beyond the basics. Knowing what is due to be paid, distinguishing obligations between those to be paid soon, and those due at a later date, and appreciation of the difference between liabilities and assets and equity, illustrates why understanding your liabilities is crucial to financing, and to cash flow and profit planning, and avoid surprises.
This guide explains what liabilities are, the main types, how contingent liabilities are handled, how liabilities compare with assets, and the key ratios used to assess them.
What Are Liabilities in Accounting?
A liability is a present obligation to give up economic resources, usually cash, to someone else as a result of something that has already happened. Put simply, it's money or services the business owes.
Liabilities are recorded on the balance sheet and represent claims against the business's assets. They're part of the basic accounting equation:
Assets = Liabilities + Equity
Every asset the business has is funded one of two ways. Either it was paid for with borrowed money or unpaid obligations, which are liabilities, or it was funded by the owners through investment and retained profit, which is equity.
Types of Liabilities
Current Liabilities
Current liabilities are obligations due within 12 months. They are settled using current assets (cash, receivables) and represent the business's short-term financial obligations.
| Current Liability | Description |
|---|---|
| Accounts payable | Amounts owed to suppliers for goods/services received but not yet paid |
| Accrued expenses | Costs incurred but not yet invoiced or paid (salaries, utilities, interest) |
| Short-term loans | Borrowings due for repayment within the next 12 months |
| Current portion of long-term debt | The next 12 months' worth of principal on long-term loans |
| Taxes payable | Income tax, payroll tax, and sales tax owed but not yet remitted |
| Unearned revenue | Cash received for goods/services not yet delivered |
| Customer deposits | Refundable advances from customers |
Non-Current (Long-Term) Liabilities
Non-current liabilities are obligations due beyond 12 months. They represent the business's longer-term debt and commitments.
| Non-Current Liability | Description |
|---|---|
| Long-term debt / bank loans | Borrowings with repayment schedules beyond 12 months |
| Mortgage payable | Property loan secured by real estate |
| Deferred tax liabilities | Taxes that will be payable in the future due to timing differences between accounting and tax treatment |
| Lease obligations (right-of-use) | Long-term lease liabilities under ASC 842 / IFRS 16 |
| Pension obligations | Defined benefit pension commitments |
Contingent Liabilities
Contingent liabilities are potential obligations that depend on the outcome of a future event, typically disclosed in the notes to financial statements rather than recognised on the balance sheet. Examples: pending litigation, warranty obligations, guarantees of third-party debt. They are recorded on the balance sheet only if the obligation is probable and the amount can be reasonably estimated.
When I look at a small business's balance sheet, the first number I check is the current ratio: current assets against current liabilities. Profit can look fine while that ratio is below one, which means the bills due in the next year are bigger than the cash and receivables available to pay them. That's the business that ends up stretching suppliers and missing tax payments, even in a good year.
Abhinav Gupta, CPA, CA, MBA · LinkedInLiabilities vs Assets
| Assets | Liabilities | |
|---|---|---|
| Definition | Resources the business owns or controls | Obligations the business owes to external parties |
| Balance sheet side | Left side (or top in vertical format) | Right side (or middle in vertical format) |
| Examples | Cash, inventory, equipment, receivables | Accounts payable, loans, accrued expenses |
| Effect on equity | Higher assets = higher equity (all else equal) | Higher liabilities = lower equity (all else equal) |
| Cash flow | Increases often use cash (buying assets) | Decreases often use cash (paying liabilities) |
Key Liability Ratios
| Ratio | Formula | Interpretation |
|---|---|---|
| Debt-to-Equity (D/E) | Total Liabilities / Total Equity | D/E > 2.0 indicates high leverage; varies significantly by industry |
| Current Ratio | Current Assets / Current Liabilities | >1.5 is healthy; <1.0 suggests short-term liquidity risk |
| Debt-to-Assets | Total Liabilities / Total Assets | <0.5 (50%) means assets are primarily equity-funded |
| Interest Coverage | EBIT / Interest Expense | >3.0x is generally comfortable; <1.5x is concerning |
Many lenders also look at the debt service coverage ratio, which compares the cash a business generates with its total loan payments, including principal. It's often the deciding number on a small business loan application.
How to Keep Liabilities Under Control
Track What's Due and When
Keep an up-to-date view of every obligation and its due date, including tax payments, loan installments, and supplier terms. Your accounts payable aging report and a cash flow forecast together will show what's coming.
Match Debt to What It Funds
Use short-term financing for short-term needs, like covering inventory or a timing gap in receivables. Use long-term loans for long-term assets, like equipment or property. Funding a five-year asset with a revolving line of credit puts unnecessary pressure on cash.
Don't Forget the Hidden Liabilities
Sales tax collected, payroll taxes withheld, accrued wages, and customer deposits are all real obligations, even though no one sends you a bill for them. Keep that cash set aside rather than treating it as available to spend.
Review Your Ratios Regularly
Check your current ratio and debt levels at least quarterly, and before taking on any new financing. A steady decline is much easier to fix when you spot it early.
Conclusion
Liabilities aren't something to fear. Every growing business has them, and used well they fund equipment, inventory, and expansion. What matters is understanding exactly what you owe, when it's due, and how it compares with the assets and cash available to cover it. Keep track of both the obvious and less visible obligations, match your financing to its purpose, and review your key ratios regularly, and your liabilities will support the business instead of constraining it.
Book a free consultation and we will check what is missing.
Frequently Asked Questions
Are liabilities bad for a business?
Not necessarily. Liabilities are one of the main ways businesses access resources to grow. A mortgage lets you own property, an equipment loan funds machinery, and supplier credit gives you time between receiving goods and paying for them. The real question is whether your liabilities are backed by productive assets and whether the business can comfortably keep up with the payments.
What's the difference between a liability and an expense?
An expense is the cost of using up a resource in a given period, and it reduces profit on the income statement. A liability is an obligation to pay in the future, and it sits on the balance sheet until it's settled. When you incur an expense but haven't paid for it yet, it's recorded as both an expense and a liability, such as an accrued expense. Some liabilities, like the principal on a loan, never become expenses at all. Only the interest shows up on the income statement.
Is unearned revenue a liability?
Yes. When a customer pays before you deliver, you owe them the product or service, so the payment is recorded as a liability. It moves to revenue as you fulfill the order or provide the service.
What's the difference between current and long-term liabilities?
Current liabilities are due within 12 months of the balance sheet date, while long-term liabilities are due after that. The split matters because current liabilities have to be paid from the cash and receivables you have now, which makes them central to judging short-term financial health.
How do I reduce my business's liabilities?
Start with the most expensive debt, such as high-interest credit cards or lines of credit. Paying suppliers on time, avoiding unnecessary short-term borrowing, and building a cash reserve all help. Refinancing short-term debt into longer-term loans won't reduce what you owe, but it can ease pressure on cash by lowering the payments due within the year.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Balance Sheet Looking Too Healthy?
Book a free consultation and we will check what is missing.