Insurance agencies operate within one of the most financially and regulatorily complex business environments in the United States. Unlike many service-based businesses, agencies must manage commission income, carrier payables, trust accounts, premium collections, policy-related transactions, and detailed reporting requirements while maintaining strict compliance standards. Even relatively small accounting errors can create reconciliation issues, reporting inaccuracies, or regulatory concerns that take significant time and resources to resolve.
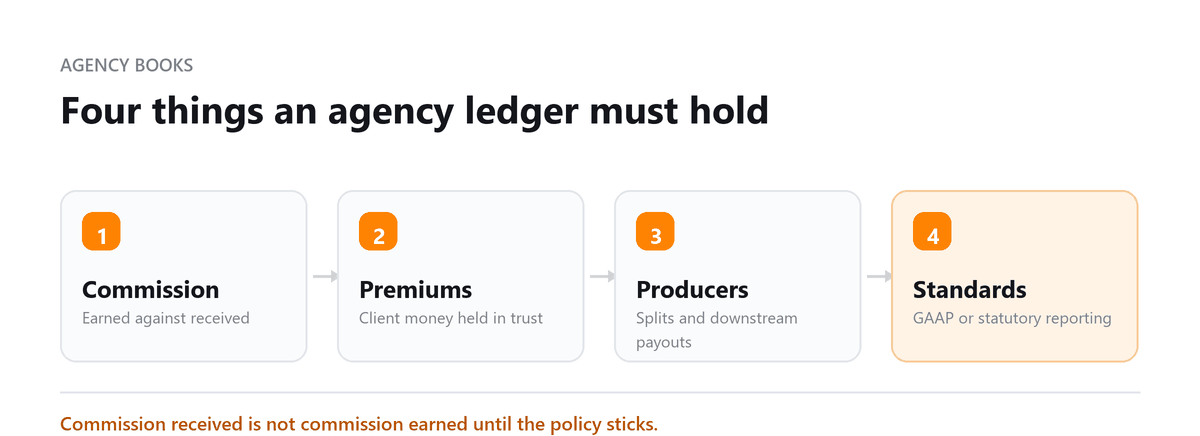
What makes insurance agency bookkeeping particularly challenging is the need to manage multiple layers of financial reporting simultaneously. Agencies often need to navigate Generally Accepted Accounting Principles (GAAP), Statutory Accounting Principles (SAP), state regulatory requirements, and carrier-specific reporting obligations. Premium transactions, commission structures, unearned revenue calculations, and trust account management all require a level of specialization that extends well beyond traditional bookkeeping practices.
Accurate bookkeeping provides insurance agency owners with more than compliance support. It delivers visibility into profitability by line of business, carrier relationships, commission performance, operating expenses, and cash flow trends. With reliable financial data, agency leaders can make informed decisions about growth initiatives, acquisitions, staffing, and operational improvements while reducing regulatory risk.
Insurance agency bookkeeping is not simply about recording transactions. It is about maintaining financial accuracy in a highly regulated industry where compliance, reporting integrity, and operational visibility are critical. Agencies that invest in specialized bookkeeping support are better positioned to manage risk, improve decision-making, and support long-term growth.
Insurance agency bookkeeping has layers that most general bookkeepers are not prepared for premium reserves, unearned premium calculations, loss ratios, and the intersection of GAAP and SAP. An agency using a general bookkeeper instead of an insurance-specialist is taking a compliance risk.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhy Insurance Agency Bookkeeping is Different
Standard business bookkeeping tracks income and expenses. Insurance agency bookkeeping must also manage:
- Premium tracking: Recording gross written premiums, ceded premiums, and net retained amounts
- Commission calculations: Accurately calculating agent commissions, overrides, and contingency income
- GAAP vs SAP compliance: Understanding when each framework applies and maintaining records accordingly
- Claims processing: Recording reserves, paid claims, and recovery amounts in the correct period
These requirements demand a chart of accounts, reporting structure, and software configuration that are purpose-built for the insurance industry.
Common Accounting Errors in Insurance Agencies
| Error | Impact | Solution |
|---|---|---|
| Inaccurate Chart of Accounts | Reporting errors, misclassified transactions | Build a customised chart of accounts for the agency's specific needs |
| Missing Documentation | Audit difficulties, fraud risk | Maintain invoices, receipts, contracts, and policy documents for all transactions |
| Untimely Data Entry | Backlogs, inaccurate financial reports | Schedule daily or weekly data entry sessions; use automation to reduce lag |
| Infrequent Reconciliation | Undetected errors, compliance issues | Perform monthly or quarterly bank reconciliation as a non-negotiable process |
| Inadequate Internal Controls | Fraud risk, financial mismanagement | Segregate duties: separate staff for cash receipts and cash disbursements |
Optimising Financial Management for Insurance Agencies
Invest in Specialised Software
General accounting software cannot handle the specific workflows of an insurance agency. Consider platforms purpose-built for the industry:
- AgencyBloc: Policy management, commission tracking, and CRM in one platform
- Xactimate: Claims estimating and settlement, particularly strong for P&C carriers
- Applied Systems (Epic/TAM): Enterprise-grade agency management with full accounting integration
Partner with a CPA Who Knows Insurance
Your accountant should be fluent in both GAAP and SAP, understand unearned premium reserve calculations, and have experience preparing insurance agency financials for regulatory review.
Embrace Automation
Modern agency management systems can automate data entry for premium receipts, commission disbursements, and carrier reconciliations. Automation reduces error rates and frees staff for higher-value tasks.
Prioritise Regular Reporting
Produce and review the following reports on a fixed schedule:
- Income statement: Monthly, comparing actual vs budget
- Balance sheet: Quarterly, with attention to reserve adequacy
- Cash flow statement: Monthly
- Loss ratios: Quarterly, by line of business
Foster Cross-Department Collaboration
Accurate financials require timely data from sales, underwriting, and claims. Establish clear protocols for when and how each team submits financial information to the accounting function.
Addressing Specific Challenges
- Reconciling premium reserves: Set up sub-ledgers for each carrier and reconcile to carrier statements monthly
- GAAP/SAP compliance: Work with a compliance officer or specialist CPA to maintain dual-basis records where required
- Cybersecurity measures: Insurance agencies hold sensitive client data, implement encrypted storage, role-based access controls, and regular security audits
The Case for Outsourcing Insurance Agency Bookkeeping
Many insurance agencies find that outsourcing bookkeeping to a specialist firm delivers clear advantages:
- Reduced costs: Outsourcing eliminates the overhead of a full-time bookkeeper plus benefits
- Improved efficiency: Specialists complete tasks faster using dedicated workflows
- Compliance confidence: Specialist firms stay current on SAP changes and regulatory requirements
- Focus on core business: Agency principals spend time selling and managing relationships, not reconciling ledgers
- Scalability: Outsourced capacity expands as the agency grows, no hiring lag
At Profitjets, we have worked with insurance agencies that believed their books were accurate because basic financial reports appeared balanced. However, deeper reviews often revealed issues with carrier reconciliations, commission tracking, premium allocations, or reserve-related calculations that had accumulated over time. In several cases, correcting these issues not only improved financial reporting accuracy but also reduced compliance exposure and strengthened confidence in management reporting.
We have also seen agencies relying on general bookkeeping support that lacked insurance-specific expertise. Insurance accounting involves complexities that many traditional bookkeepers rarely encounter, including premium trust accounting, commission reconciliations, unearned premium calculations, loss ratio reporting, and the interaction between GAAP and SAP requirements. These are specialized areas where errors can have consequences that extend beyond ordinary bookkeeping mistakes.
Conclusion
Insurance agency accounting is a specialist discipline. The agencies that get it right operate with stronger compliance posture, cleaner carrier relationships, and better visibility into their own profitability. Whether you build that capability in-house or partner with a specialist firm, investing in proper bookkeeping infrastructure is one of the highest-return decisions an agency owner can make.
Book a free consultation and we will set the commission tracking up properly.
Frequently Asked Questions
What is the difference between GAAP and SAP for insurance?
GAAP (Generally Accepted Accounting Principles) is used for external financial reporting to investors and lenders. SAP (Statutory Accounting Principles) is required by state insurance regulators and is more conservative, emphasising solvency. Some agencies must maintain records under both frameworks.
Do insurance agencies need specialised bookkeeping software?
Yes. General accounting platforms like QuickBooks cannot natively handle premium tracking, commission calculations, or carrier reconciliation workflows. Insurance-specific platforms such as AgencyBloc or Applied Systems are strongly recommended.
How often should an insurance agency reconcile its accounts?
Bank accounts and carrier statements should be reconciled at least monthly. Premium trust accounts, if applicable, may require weekly reconciliation to meet state regulatory requirements.
What records should an insurance agency keep for audit purposes?
Retain all policy documents, premium receipts, commission statements, carrier remittances, claims files, and financial statements for a minimum of five to seven years, or as required by your state insurance department.
When should an insurance agency outsource its bookkeeping?
Consider outsourcing when internal staff are spending more than a few hours per week on bookkeeping tasks, when compliance errors are recurring, or when the agency is growing faster than its accounting infrastructure can keep up.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Want Agency Books to Standard?
Book a free consultation and we will set the commission tracking up properly.