
Leaving California can be an extremely expensive proposition, for a number of residents who are willing to make the move. In addition, the Franchise Tax Board (FTB) is always looking to take advantage of California residents, even those who reside outside the state. Many California residents are surprised to find out that the FTB will pursue them even if they leave the state, and that they would be responsible for any income generated inside California from doctors, banks and businesses that remain there.
If you are contemplating an exit strategy from the state of California, simply updating your address with the DMV and your voter registration is not going to be sufficient, even if you find a foolproof way to time your exit so as to avoid paying taxes on your unrealized gains.
In this article we will discuss some of these issues, as well as how residents can properly time their exits so as not to encounter difficulties with the FTB.
The single most critical step a high-income resident must take before leaving California is establishing a physical and intent-based paper trail of domicile change months before triggering major liquidity events like exercising stock options/ selling a business.
Anu Gupta, CA, EA, B.Tech · LinkedInWhat Is the California Exit Tax?
'Exit tax' is an informal term for the taxes triggered when a California resident changes domicile or moves a business out of California. California can claim tax on income earned during the year of departure, and, in some cases, on deferred income that is attributable to the California residency period.
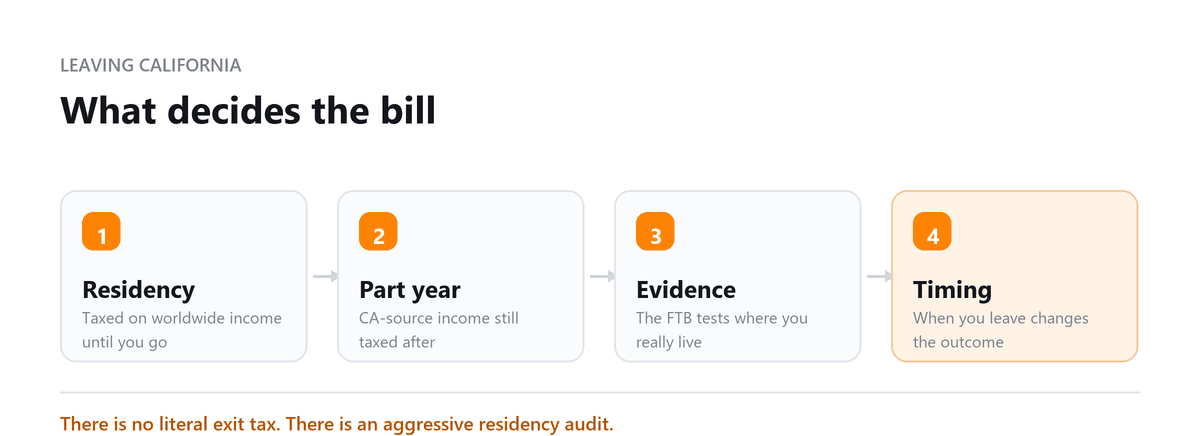
- California taxes residents on worldwide income until the day of departure
- Part-year residents pay CA tax on California-source income for the full year and on worldwide income during the CA residency period
- California's Franchise Tax Board aggressively audits high-income departures
How Does California's Exit Tax Work?
Failure to understand the mechanics of California exit tax, or how one can legally establish a new residence without exposing all one’s assets to the long reach of the FTB can result in residents being liable for thousands of dollars they may not be aware of.
When a California resident changes domicile, California taxes:
- All income earned from January 1 to the departure date
- Stock options, RSUs, and deferred compensation that vested during California residency (even if exercised or paid after departure)
- Business sale proceeds attributable to goodwill and intangibles developed in California
- IRC Section 1374 built-in gains (C Corp converting to S Corp)
Key Triggers for California Tax on Departure
| Trigger | California Tax Claim |
|---|---|
| Changing domicile mid-year | Worldwide income taxed until departure date |
| Deferred stock options (RSUs, ISOs) | CA claims tax on the CA-vested portion, regardless of residence at exercise |
| Selling a California-based business | Capital gains on CA-source goodwill taxable by CA |
| S-Corp with prior C-Corp history | IRC 1374 built-in gains may be taxable in CA |
| Lottery / deferred prize | CA taxes the CA-period accrual |
Exit Tax Strategy: How to Minimise California Tax
- Establish clear domicile change: formal acts including driver's licence, voter registration, bank accounts, social connections in new state
- Spend no more than 546 days in California over two years after departure (safe harbour)
- Accelerate income into California while still a resident if the new state has no income tax (e.g. Texas, Nevada, Florida)
- Exercise stock options before departure if CA tax rate < new state rate on the vested gain
- Transfer business to a new state structure before departure, but get proper legal and tax advice on timing
- Use qualified opportunity zone (QOZ) investments to defer and potentially reduce gain on California assets
California Residency Audit Risk
The FTB has a dedicated out-of-state audit unit. Triggers for audit include:
- Income over $500,000 in the year of departure
- Significant California-source income after claiming non-residency
- Continued business operations, property ownership, or family ties in California
- Social media posts, credit card transactions, or phone data showing extended California presence
At Profitjets, our tax advisory team brings 15+ years of experience in multi-state tax planning, helping high-net-worth individuals and business founders navigate high-risk state departures.
When a tech executive client approached us prior to moving to Texas, they held significant unvested RSUs and stock options that were about to trigger a massive capital gain. Had they moved without a clear strategy, California’s Franchise Tax Board would have claimed state tax on the full vested amount. We structured a strict 18-month domicile exit plan, documented physical presence parameters under safe-harbor guidelines, and managed the exact timing of their stock exercises successfully insulating over $1.2 million in gains from California state tax exposure.
Conclusion
California's exit tax is not a single levy but a combination of residency rules, source-income claims, and equity compensation tracing that can follow departing residents for years. Proper planning beginning 12 to 24 months before departure, is essential for high-income individuals and business owners.
To date, Profitjets has guided over 40 high-income clients through California exit planning, saving them an average of $180,000 per engagement by strategically timing equity exercises and establishing clean domicile transitions.
Book a free consultation and we will plan the timing and the evidence.
FAQs
Does California have an exit tax?
Not a single named tax, but California taxes worldwide income up to departure date, taxes deferred equity compensation attributable to California residency, and claims tax on California-source business income even after departure. The combination is often called an 'exit tax' informally.
How long do I need to be gone from California to avoid taxes?
There is no minimum. The key is establishing domicile in a new state. California's safe harbour is 546 days outside California over two years for individuals who change domicile. However, FTB can audit residency at any time within the statute of limitations.
Can California tax my income after I move out?
Yes. for California-source income (rental income from CA property, wages from CA employers, business income from CA operations) and for equity compensation that vested during California residency, regardless of when exercised.
What is a part-year California resident?
A part-year resident is someone who is a California resident for part of the tax year and a nonresident for the remainder. This commonly applies when someone moves into or out of California during the year. California generally requires part-year residents to report income received while they were residents as well as California-source income earned during the nonresident period.
Can I move out of California but keep my California business?
Yes, but moving your personal residence does not necessarily remove California tax obligations connected to a business. If you continue operating a business in California or receive California-source business income, California filing and tax requirements may still apply depending on the business structure and activities.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Planning a Move Out of California?
Book a free consultation and we will plan the timing and the evidence.