Short version: if you have an LLC or a corporation, yes, and it's not up for debate. If you're a sole proprietor or a freelancer, there is no law that forces you to, but the point at which it can be worth your time comes sooner than you'd think.
The reason is not about being neat and tidy, though. In fact, a business bank account is how you turn an LLC's liability protection into something real: commingled funds are the number one reason why courts pierce a corporation's veil and make its owners personally liable. And everything else it does for you is a bonus.
For sole proprietors the math works out differently, but you'll soon come to the same conclusion. Once you start doing any significant amount of transactions, the cost of separating them will be cheaper than undoing a jumble later.
This guide will explain when a business checking account is genuinely necessary, when it's something you should consider, how to choose one and how to transition if your accounts are already mixed.
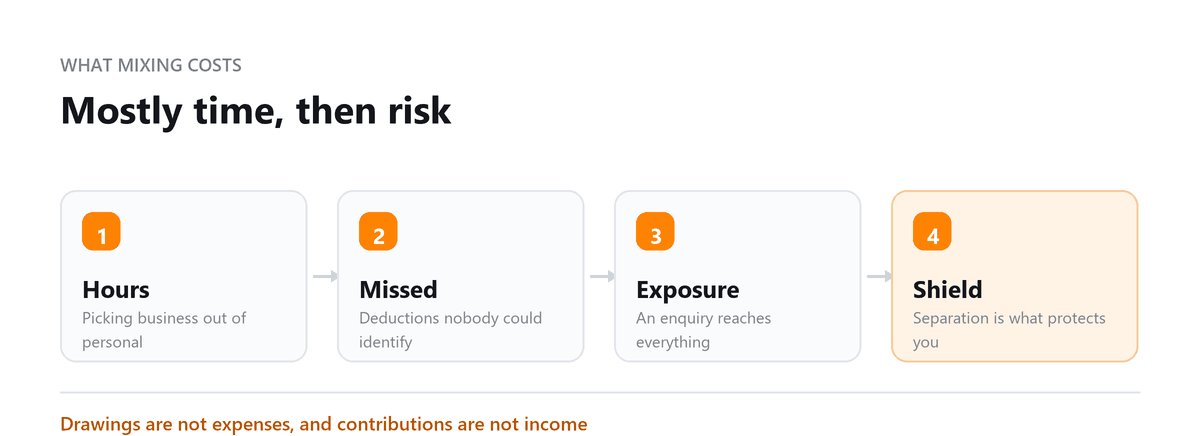
What I see in practice is a year of transactions that nobody can categorise. Business income and personal spending in one account, and at filing time the owner is going through twelve months of statements trying to remember whether a payment was a client dinner or a family one. They lose deductions they were entitled to because they can't evidence them, and they claim a few they shouldn't because the line got blurry. Both directions cost money, and the second one costs more if anybody looks.
Ankit Sagatani, MBA, B.Com · LinkedInWhat Is a Business Bank Account?
A business bank account is a bank account held in the name of a business entity (LLC, corporation, or even a DBA sole proprietorship) rather than an individual. It is separate from personal accounts and is used exclusively for business income and expenses. Business accounts come in several types: checking (for day-to-day transactions), savings (for reserves), merchant accounts (for credit card processing), and money market accounts (for higher-yield short-term reserves).
Why You Absolutely Need a Business Bank Account
- Liability protection: for LLCs and corporations, mixing personal and business funds is the primary way courts pierce the corporate veil, meaning a judge can hold you personally liable for business debts despite having an LLC. A separate business bank account is the most basic step to maintain liability protection
- Tax compliance: it is nearly impossible to accurately claim business deductions, calculate net profit, or prepare a Schedule C if business and personal expenses are mixed. Every transaction must be categorised, and mixed accounts make this exponentially harder
- Professionalism: paying vendors, employees, and contractors from a business account (with the business name on checks/transfers) looks professional and reduces confusion for payees
- Audit readiness: if the IRS or your state tax authority audits you, a clean business bank account with documented business transactions is your primary defence. Mixed accounts trigger far more scrutiny
- Credit history: business bank accounts build business credit history, required to access business loans, vendor credit terms, and corporate credit cards
Do Freelancers and Sole Proprietors Need One?
Legally, sole proprietors and freelancers (who are not LLCs or corporations) are not required to have a separate business bank account. But there are strong practical reasons to have one:
- Clean bookkeeping: separating business income and expenses simplifies tax filing and maximises legitimate deductions
- Professional invoicing: clients pay a business account rather than a personal account, important for B2B clients and enterprises
- Simplified tax preparation: with a separate account, your accountant or bookkeeper works only with business transactions, no time (and money) spent sorting through personal transactions
Recommendation: open a business bank account for any freelance or self-employed activity earning $20,000+/year or more than 20-30 transactions per month. The time and cost saved at tax time typically exceeds the account fees many times over.
How to Choose the Best Business Bank Account
| Factor | What to Look For |
|---|---|
| Monthly fee | Look for waivable fees (min balance or transaction threshold) or $0 neobank accounts |
| Transaction volume | High-volume businesses need accounts with high free transaction limits; standard checking limits 200-500 transactions/month before fees |
| Cash deposits | If you handle physical cash, you need a bank with branches or ATM deposit capability, most neobanks do not accept cash |
| Integration | Look for QuickBooks, Xero, or accounting software integration to eliminate manual data entry |
| Interest on balance | Neobanks often offer 1-4% APY on business checking balances, traditional banks typically offer near 0% |
| FDIC insurance | All US bank accounts should be FDIC-insured up to $250,000 per depositor per bank |
Future Trends in Business Banking
Business banking continues to evolve rapidly into 2026. Key trends shaping business bank account decisions:
- AI-powered financial insights: many neobanks now offer automated expense categorisation, cash flow forecasting, and anomaly detection built into the banking interface
- Real-time payments: the FedNow instant payment network (launched 2023) is expanding bank participation, real-time B2B and payroll payments are becoming standard
- Embedded finance: business tools (Shopify, QuickBooks, Gusto) are increasingly offering integrated banking keeping more financial activities within the primary business software
- Higher yield on business checking: with rates stabilising after the 2022-2024 rate cycle, business accounts with meaningful APY are more available than they were pre-2022
Book a free consultation and we will separate it cleanly.
Frequently Asked Questions
Is a business bank account required for an LLC?
No federal law requires one, but functionally you need it. The liability protection you formed the LLC for depends on operating it as genuinely separate, and commingled funds are the most common factor in cases where courts disregard the entity. Treat it as a requirement even though it isn't technically one.
Can I use a personal account temporarily?
A sole proprietor can, with the accounting cost that follows. For an LLC or corporation it directly undermines the liability shield, and since business accounts are free at several providers, "temporary" is rarely worth what it risks. If you've already been doing it, open the account now and move the flows, the break is what matters.
What documents do I need?
Typically an EIN, your Articles of Incorporation or Organisation, an operating agreement or bylaws, government ID for each owner above a significant ownership threshold usually 25% and a business address. Fintech platforms often need less; traditional banks usually want more, including an SSN or ITIN.
Do I need a separate account for each business I run?
Yes, if they're separate legal entities. Two LLCs sharing one account has the same problem as mixing business and personal money, and arguably worse, since it undermines both entities' separation. If they're two DBAs under one sole proprietorship, one account is defensible, though separate ones make the bookkeeping considerably easier.
Does a business bank account build my business credit?
Not directly. Business credit files are built through trade credit, business credit cards and loans that report to commercial bureaus. The account is what gives you access to those products necessary, but not sufficient on its own.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Still Running Through One Account?
Book a free consultation and we will separate it cleanly.