
What is Cash Basis Accounting?
Cash basis accounting is the simpler of the two primary accounting methods. Under cash basis, a business records income only when cash is actually received from customers, not when the invoice is issued, and records expenses only when cash is actually paid to vendors or employees, not when the bill arrives.
This approach mirrors your bank account. If a customer owes you $10,000 but has not paid yet, that $10,000 does not appear in your income under cash basis. The method works best for small businesses with minimal inventory, immediate payment practices, and straightforward operations, typically sole proprietors, freelancers, and small service businesses.
The question isn't just which method is simpler, it's which one gives you financial statements your bank and investors will trust. Cash basis can actually hurt you when you go to raise capital, because it obscures your true revenue position.
Ankit Sarawagi, CPA, CA, MBA · LinkedInBenefits of Cash Basis Accounting
- Simplicity: Fewer accounting entries, no need to track receivables and payables, and straightforward reconciliation with bank statements.
- Reflects actual cash on hand: The books show money you have actually received, not money owed to you, reducing the risk of spending based on paper profits.
- Easier tax management: For eligible businesses, cash basis often allows more flexibility in timing income and deductions to manage tax liability.
What is Accrual Accounting?
Accrual accounting records income when it is earned, when goods are delivered or services are performed, and records expenses when they are incurred, regardless of cash timing. Accounts receivable, accounts payable, prepaid expenses, and accrued liabilities all appear on an accrual-basis balance sheet.
Accrual accounting provides a comprehensive financial snapshot. It shows not just how much cash you have but how much you are owed, how much you owe, and what your true obligations are at any point in time. This comprehensive view is why lenders, investors, and the IRS require it for larger businesses.
Benefits of Accrual Accounting
- Matches revenues to periods: Income and the expenses that generated it are recorded in the same period, giving a true picture of profitability.
- Accurate financial picture: Receivables, payables, and accruals are all captured, essential for businesses with significant outstanding invoices or inventory.
- Required for growth: Businesses seeking investment, bank loans, or strategic partnerships almost always need accrual-based financial statements.
Cash vs Accrual for Small Business: Which is Better?
Cash Basis: Best for Simplicity
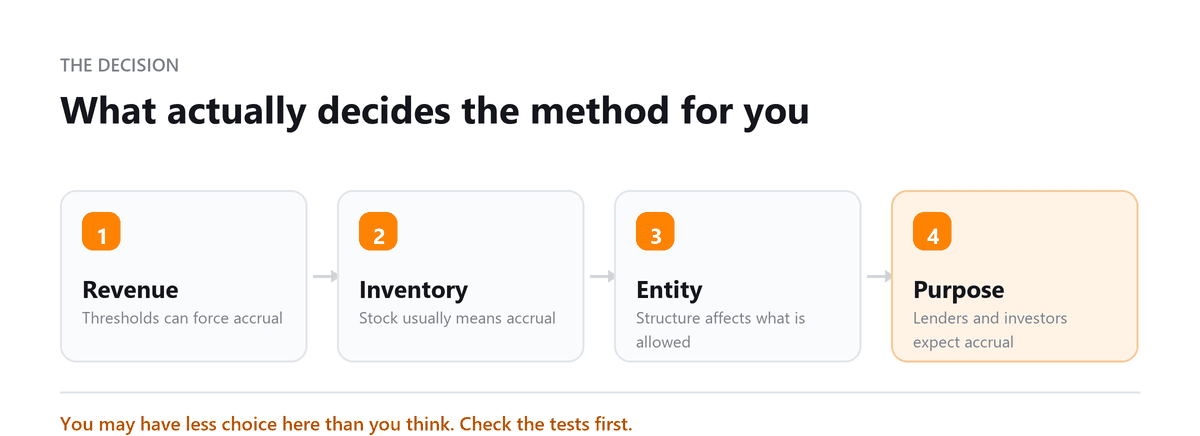
Cash basis suits service businesses, freelancers, and small operations with low transaction volume, few outstanding invoices, and simple financial structures. If you collect payment at the time of service and rarely carry receivables or payables, cash basis may be adequate and legally permissible.
Accrual: Best for Growth
Accrual accounting is appropriate for businesses with inventory, credit sales, multiple employees, and complex vendor relationships. It is also necessary if you are seeking outside investment or bank financing, as lenders routinely require accrual-based financials. The additional complexity pays for itself in financial visibility and credibility.
What are the IRS Requirements for Cash and Accrual Accounting?
The IRS imposes accrual accounting requirements on businesses that exceed a certain size. Under IRC §448, C corporations and businesses with average annual gross receipts exceeding the applicable threshold must use accrual accounting. The threshold is adjusted for inflation, for 2026, this figure is approximately $29 to $32 million.
Businesses below the threshold generally have the freedom to choose either method, though switching methods requires IRS consent via Form 3115.
What is the Accrual Method of Accounting?
The accrual method is the accounting approach required by GAAP and IFRS for external financial reporting. It recognizes economic events when they occur rather than when cash moves. Revenue is recognized when performance obligations are satisfied; expenses are recognized when goods or services are consumed. This timing alignment, called the matching principle, produces financial statements that accurately represent the economic performance of the period.
What is the difference between cash basis and accrual accounting?
The fundamental difference is timing. Under cash basis, the trigger for recording is cash movement. Under accrual, the trigger is economic activity, earning revenue or incurring an expense, regardless of when cash changes hands. Cash basis is simpler and shows your cash position; accrual is more complex and shows your true financial position including obligations and entitlements.
Why would a small business choose accrual accounting?
A small business typically moves to accrual accounting for one of three reasons: it is growing and needs better financial visibility for management decisions; it is seeking a bank loan or investment and needs credible financial statements; or its revenue and complexity have crossed the point where cash basis no longer gives an accurate picture of profitability. Many businesses switch proactively rather than waiting for the IRS threshold.
Is cash or accrual accounting better for taxes?
Cash basis offers more flexibility for tax timing, you can defer income into the next tax year by delaying invoicing at year end, or accelerate deductions by prepaying expenses in December. Accrual accounting is more predictable but less flexible, income is recognized when earned, regardless of whether you have been paid yet. For businesses in volatile years or those trying to manage tax liability actively, cash basis timing flexibility can be valuable.
How Profitjets Can Help
Profitjets helps businesses assess which accounting method is right for their stage and situation, manages the transition from cash to accrual when the time comes, and handles all IRS Form 3115 requirements for method changes. Our team builds the bookkeeping infrastructure that makes either method run smoothly.
Conclusion
Cash basis and accrual accounting are not equally suited to every business. The right choice depends on your size, industry, growth trajectory, and stakeholder requirements. Most businesses start with cash basis for simplicity and eventually migrate to accrual as they grow, the question is whether you make that transition proactively or wait until circumstances force it.
From the Profitjets Team
Book a free consultation and we will check the tests against your numbers.
Frequently Asked Questions
Is cash basis accounting legal for all businesses?
Cash basis is legal for most small businesses, but there are exceptions. C corporations and businesses with average annual gross receipts exceeding the IRS §448 threshold (approximately $29 to $32M for 2026) must use accrual accounting.
Can I use cash basis for my books but accrual for taxes?
Generally no, you should use the same method for both unless you maintain two separate sets of records (which is complex and costly). Consult a CPA if your situation creates a mismatch.
How does cash basis accounting affect loan applications?
Lenders typically prefer or require accrual-based financials because they show a more complete picture of receivables, payables, and obligations. Cash basis statements may lead lenders to underestimate your true revenue or overstate your risk.
What happens to outstanding invoices under cash basis accounting?
They don't appear in your income until the customer pays. This means your accounts receivable balance isn't reflected in your revenue, which can make your income look lower than it actually is on a business-performance basis.
Do I need to notify the IRS if I change accounting methods?
Yes. Changing from cash to accrual (or vice versa) requires filing IRS Form 3115 (Application for Change in Accounting Method). Most businesses need IRS consent before making the change.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Right Basis Confirmed?
Book a free consultation and we will check the tests against your numbers.