
Form 8804 is the Annual Return for Partnership Withholding Tax under Section 1446. Partnerships with foreign partners that have effectively connected income (ECI) must withhold tax and report it on Form 8804. This form is the partnership's annual summary of withholding; individual partner withholding is reported on Form 8805.
When a US partnership or multi-member LLC has a foreign partner, it takes on a responsibility many owners don't expect. The partnership must pay withholding tax on the foreign partner's share of US business income, whether or not any cash was actually distributed.
Many smaller partnerships with an overseas investor or co-founder only find out when the year-end return is being prepared.
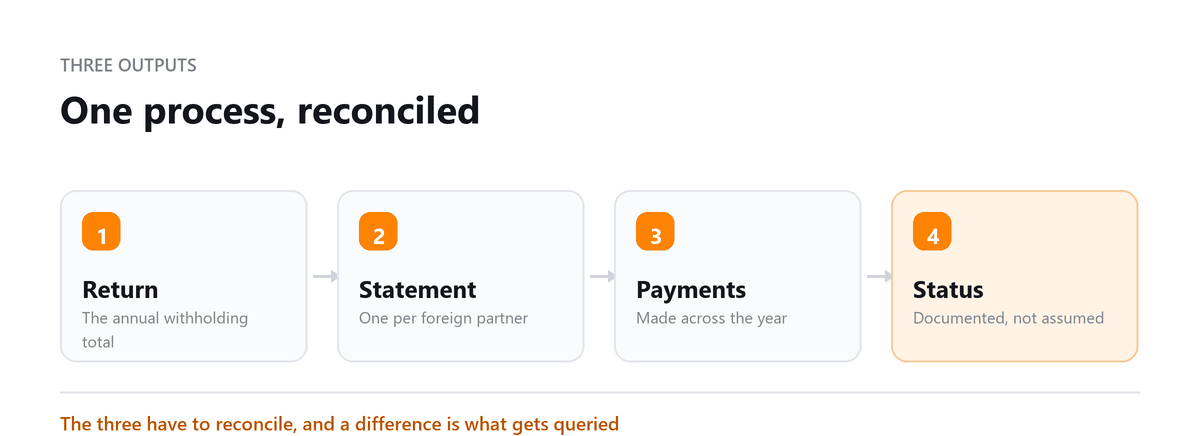
The requirement comes from Section 1446. A partnership with effectively connected taxable income allocable to foreign partners must pay withholding tax at the highest applicable US rates, generally in quarterly installments using Form 8813.
At year-end, it files Form 8804 to report the total and gives each foreign partner a Form 8805 showing their share. A separate set of rules under Section 1446(f) applies when a foreign person sells an interest in a partnership.
For US partnerships formed with founders or investors abroad, withholding needs to be part of the tax calendar from the first quarter.
Expert Perspective
The Section 1446 problem I see most often is timing. A partnership with a foreign member calculates everything correctly at year-end, but it never pays the quarterly installments, so penalties and interest have already built up. If any partner or LLC member is a nonresident, withholding needs to be built into the quarterly estimate process from the start, not discovered when the return is prepared.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat Is Form 8804?
U.S. partnerships with foreign partners must withhold income tax on that partner's allocable share of effectively connected income (ECI), income from U.S. trade or business operations.
Getting this wrong leaves the partnership liable for the tax that should have been withheld, plus penalties and interest. Foreign partners also depend on Form 8805 to claim credit for the tax on their own US returns.
Section 1446 requires:
- Withholding at the highest applicable tax rate on each foreign partner's distributive share of ECI
- Quarterly installment deposits (Form 8813)
- Annual reconciliation and reporting on Form 8804 (for the partnership) and Form 8805 (for each foreign partner)
Who Must File Form 8804?
- Any domestic or foreign partnership with one or more foreign partners AND effectively connected income or loss for the year
- The partnership files Form 8804 even if there is no ECI for the year if it had foreign partners during the year
- Exception: partnerships with no ECI and no foreign partners do not file
Filing Deadline for Form 8804
Annual Return Due Date
Form 8804 is generally due by the 15th day of the third month after the partnership's tax year ends, the same due date as Form 1065. For calendar-year partnerships, that's March 15. When the due date falls on a weekend or legal holiday, it moves to the next business day, so 2025 returns were due March 16, 2026.
Partnerships that keep their books and records outside the United States and Puerto Rico generally have until the 15th day of the sixth month after year-end, which is June 15 for calendar-year partnerships.
Copies of Form 8805 must be given to each foreign partner by the due date of Form 8804, including extensions.
Extension
Filing Form 7004 by the original due date gives an automatic six-month extension to file Form 8804, moving the calendar-year deadline to September 15.
The extension only covers the filing. Any withholding tax that wasn't paid through quarterly installments is still due by the original deadline, and penalties and interest apply to late payments.
Quarterly Installment Payments
Partnerships must generally pay the Section 1446 withholding tax during the year in installments, using Form 8813. Payments are due by the 15th day of the fourth, sixth, ninth, and twelfth months of the partnership's tax year.
| Installment | Calendar-Year Due Date |
|---|---|
| 1st | April 15 |
| 2nd | June 15 |
| 3rd | September 15 |
| 4th | December 15 |
Missed or underpaid installments can trigger a penalty for underpayment of estimated Section 1446 tax, calculated on Schedule A of Form 8804, even if the full amount is paid when the return is filed.
Related Forms
| Form | Purpose |
|---|---|
| Form 8805 | Foreign Partner's Information Statement, issued to each foreign partner; shows their withholding credit |
| Form 8813 | Partnership Withholding Tax Payment Voucher, quarterly installment deposits |
| Form 7004 | Application for automatic 6-month extension to file Form 8804 |
| Schedule K-1 | Reports each foreign partner's share of income, ECI, and withholding |
Step-by-Step: Completing Form 8804
- Part I: Identify the partnership (name, EIN, tax year) and total number of foreign partners
- Part II: Report total ECTI (effectively connected taxable income) allocable to all foreign partners combined
- Part III: Calculate total withholding required at applicable tax rates (37% for individuals; 21% for foreign corporations)
- Part IV: Credit for installment payments already made via Form 8813
- Balance due or overpayment: pay with Form 8804-C or apply to next year
- Attach Form 8805 for each individual foreign partner
Book a free consultation and we will handle the withholding filings.
Frequently Asked Questions
Who must file Form 8804?
A partnership, including an LLC taxed as a partnership, must file Form 8804 if it has effectively connected taxable income allocable to one or more foreign partners. The obligation applies whether or not the partnership makes distributions. A single-member LLC owned by a foreign person is generally a disregarded entity, not a partnership, so different rules apply.
What withholding rate applies?
Withholding is generally calculated at the highest US tax rate for the type of foreign partner: the top individual rate, currently 37 percent, for noncorporate partners, and the corporate rate of 21 percent for corporate partners. In some cases, a partnership can take certain partner-level deductions or losses into account if the partner provides the required certification.
When is Form 8804 due, and when are payments made?
Form 8804 is generally due by the 15th day of the third month after the partnership's tax year ends, which is March 15 for calendar-year partnerships. Form 7004 extends the filing deadline but not the payment deadline. Installment payments are generally due on the 15th day of the fourth, sixth, ninth, and twelfth months of the tax year, using Form 8813.
What does a foreign partner do with Form 8805?
The foreign partner attaches Form 8805 to their US income tax return, typically Form 1040-NR for individuals or Form 1120-F for corporations, and claims a credit for the tax withheld. If the withholding exceeds their actual US tax, they can generally receive a refund of the difference.
Is Section 1446(f) withholding the same as Form 8804 withholding?
No. Section 1446(f) applies when a foreign person sells or otherwise transfers an interest in a partnership engaged in a US trade or business. The buyer is generally required to withhold 10 percent of the amount realized, and in some cases the partnership must withhold from distributions to the buyer if the buyer fails to. That withholding is reported on separate forms from Form 8804.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Foreign Partners in Your Partnership?
Book a free consultation and we will handle the withholding filings.