
A US founder forms an overseas company with foreign partners. A family puts money in with relatives into an overseas partnership to buy property. A US business puts equipment in a foreign joint venture.
Any of these could end up causing Form 8865, one of the most penalty-heavy information returns around, and a form many people don't know about until long after the investment has occurred.
Form 8865 reports interests in and contributions of property to foreign partnerships, and changes to ownership interests.
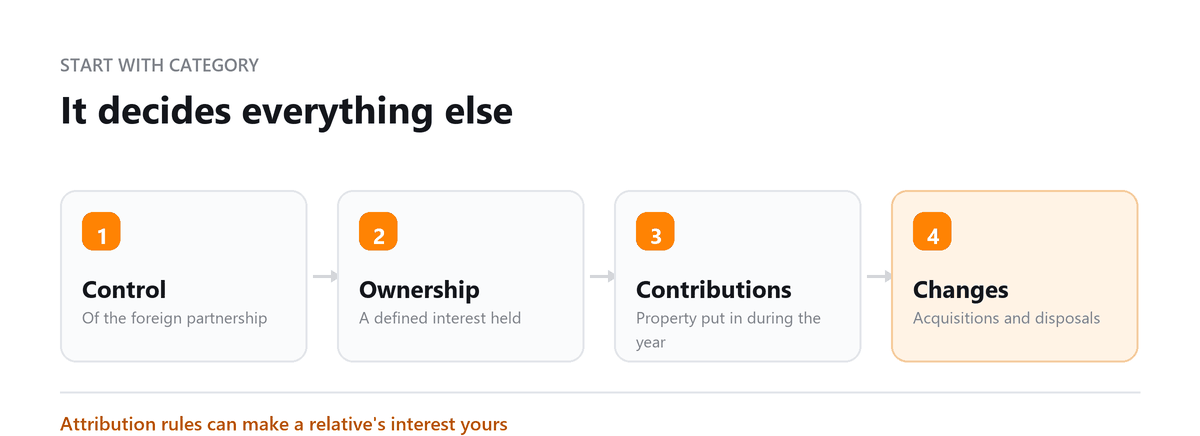
There are four types of filers, each with different schedules, depending on whether they control the partnership, have a substantial interest in a US-controlled partnership, contributed property, or had an acquisition or disposition causing a change in the filer's ownership interest.
Entity classification is a key issue beneath that: a foreign entity can be classified for US tax purposes as a partnership, a corporation, or a disregarded entity, and each requires a different form.
Expert Perspective
A lot of Form 8865 problems start with classification. A business owner invests in a foreign company or joint venture and assumes it's taxed like a US LLC, or assumes it's a corporation, without checking the default rules or whether an election was ever made. The classification decides whether you file Form 8865, Form 5471, or Form 8858, and getting it wrong means filing the wrong form while the penalty clock runs on the right one.
Ankit Sarawagi, CPA, CA, MBA · LinkedInThis guide explains who has to file Form 8865, the four categories of filers, how and when to file, the penalties for failing to file, and how entity classification affects which form applies.
Filer Categories, Who Files and What They Report
Form 8865 must be filed by U.S. persons who have certain ownership interests in or transactions with foreign partnerships. The filing requirements vary based on your level of interest (Category 1 through 4) ranging from controlling partners to those who merely transfer property to a foreign partnership.
| Category | Threshold | What You Must File |
|---|---|---|
| Category 1 | Controlled at least 50% of the foreign partnership (by vote or value) at any time during the year | Form 8865 + all Schedules (A, B, K, K-1, L, M-1, M-2, N) |
| Category 2 | U.S. partner in a controlled foreign partnership (Category 1 applies but you're not the controlling partner) | Form 8865 + Schedule K-1 and certain other schedules |
| Category 3 | Contributed property to a foreign partnership in exchange for a partnership interest (or basis adjustment applies) | Form 8865 + Schedule O (contribution details) |
| Category 4 | Had a reportable event: acquisition, disposition, or change in proportional interest of 10%+ during the year | Form 8865 + Schedule P (acquisitions, dispositions, changes) |
Penalty for Failure to File
The penalty for failing to file Form 8865 when required is generally $10,000 per year. If the failure continues for more than 90 days after an IRS notice, an additional $10,000 penalty may apply for each 30-day period, up to $50,000.The statute of limitations for the related tax return may remain open until the required form is filed.
The penalties for failure to file are what make this such an important form. Failure to file can result in a $10,000 penalty for each form, each year, in addition to additional penalties after the IRS sends a notice, possible reductions in foreign tax credits, and a separate penalty for unreported property contributions, and a prolongation of the statute of limitations.
A review of classification and filing requirements when the investment was made is much easier than learning about this later.
Filing Deadline
Form 8865 is attached to the U.S. person's annual tax return, Form 1040 for individuals, Form 1065 for partnerships, or Form 1120 for corporations, due by the normal filing deadline including extensions. For calendar-year individual filers (TY2025): April 15, 2026 (or October 15, 2026 with extension).
Key Schedules
| Schedule | Purpose |
|---|---|
| Schedule A | Constructive ownership percentage calculation |
| Schedule B | Income and deductions from the foreign partnership |
| Schedule K / K-1 | Partner's share of income, deductions, credits |
| Schedule L | Balance sheet per books |
| Schedule M-1 | Reconciliation of income per books vs per return |
| Schedule N | Transactions between U.S. person and foreign partnership |
| Schedule O | Transfer of property to foreign partnership (Category 3) |
| Schedule P | Acquisitions, dispositions, changes in proportional interests (Category 4) |
Profitjets has managed more than 20 Form 8865 filing engagements, helping US taxpayers report interests in foreign partnerships and identify previously unreported filing obligations during tax compliance reviews.
I discovered several years after investing in a foreign joint venture that my ownership interest created a Form 8865 filing obligation. Profitjets reviewed the prior years, prepared the required catch-up filings, and helped us address the associated penalties through the applicable penalty-abatement process.
Book a free consultation and we will establish what you have to file.
FAQs
Who has to file Form 8865?
US persons, including individuals, corporations, partnerships, trusts, and estates, may have to file if they have certain interests in or transactions with a foreign partnership. Whether you file, and which parts of the form you complete, depends on which of the four filer categories applies to you during the partnership's tax year.
What are the four filing categories?
Category 1 covers a US person who controls the foreign partnership, generally by owning more than 50 percent. Category 2 covers a US person owning 10 percent or more while the partnership is controlled by US persons who each own at least 10 percent. Category 3 covers a US person who contributes property in exchange for an interest, if they own at least 10 percent afterward or contribute more than $100,000 in value within 12 months, including contributions by related persons.
Category 4 covers a US person who acquires or disposes of an interest in a way that changes their ownership by at least 10 percent or crosses the 10 percent threshold.
When and how is Form 8865 filed?
Form 8865 is generally attached to the filer's federal income tax return, or partnership return, and is due by the return's due date, including extensions. If you aren't required to file an income tax return, you generally still must file Form 8865 separately at the time and place the return would have been due.
What are the penalties for not filing Form 8865?
The basic penalty for failing to provide required information is $10,000 per foreign partnership per year. If the failure continues more than 90 days after the IRS mails a notice, additional penalties of $10,000 for each 30-day period can apply, up to $50,000. Foreign tax credits may also be reduced. Failing to report a contribution of property can carry a separate penalty of 10 percent of the property's value, generally capped at $100,000 unless the failure was intentional.
Can more than one person file a single Form 8865?
In some cases, yes. When multiple US persons qualify in the same category for the same partnership, one of them can often file the required information on behalf of the others, as long as the others include a statement with their own returns identifying the filer. The exceptions depend on the category, so review the form instructions before relying on another person's filing.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Invested in a Partnership Abroad?
Book a free consultation and we will establish what you have to file.