
Accounting is undergoing its most significant transformation in a generation. The profession is shifting from manual record-keeping and compliance execution to a strategic, technology-driven advisory function.
Cloud platforms have eliminated geography as a constraint. Artificial intelligence is automating tasks that once consumed the majority of staff time. ESG reporting is creating entirely new assurance requirements.
And digital assets are forcing the profession to develop competency in an asset class that did not exist a decade ago. Firms that adapt to these changes position themselves as indispensable advisors; those that do not risk being commoditized or replaced.
Expert Quote
This guide covers the key trends shaping the future of accounting, including artificial intelligence and automation, cloud and real-time accounting, the shift toward advisory services, outsourcing and changing tax and regulatory requirements, the accounting talent shortage, and what these trends mean for small businesses.
The accountants who will thrive in the next decade aren't the ones who are best at data entry, that work is being automated away. They're the ones who can take AI-generated numbers and translate them into business decisions their clients can act on. That's the shift: from scorekeeper to advisor.
Abhinav Gupta, CPA, CA, MBA · LinkedInKey Trends Shaping the Future of Accounting
1. AI Automation and Tax Planning
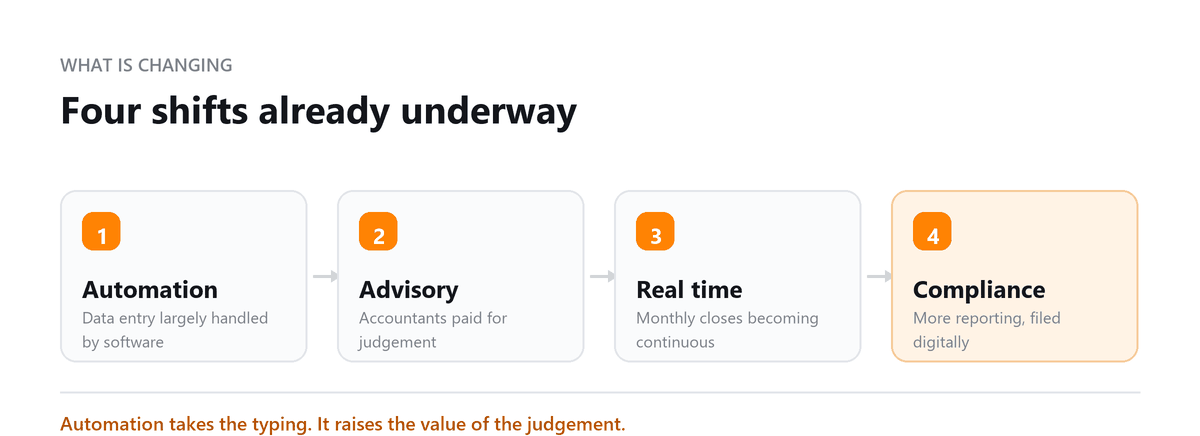
AI-driven bookkeeping is automating the tasks that have historically consumed the most staff time: data entry, transaction categorization, anomaly detection, and preliminary tax planning. Tools like QuickBooks AI, Intuit Tax Advisor, and UiPath RPA are handling workflows that previously required dedicated headcount. The implication for accounting firms is structural: data-entry roles will decline in volume, and the value of staff who can perform analytical review, identify planning opportunities, and translate AI outputs into client-ready recommendations will increase correspondingly.
Firms should be actively upskilling existing staff toward these higher-value functions rather than waiting for displacement.
2. Cloud-Based Accounting
Cloud accounting is no longer a differentiator, it is the baseline expectation. QuickBooks Online, Xero, NetSuite, Zoho Books, and Sage Intacct have made real-time collaboration between clients and accountants the standard. Clients can grant access, upload documents, and see live financial dashboards without exchanging files. The practical requirement this creates for firms is twofold: proficiency across multiple cloud platforms (clients will not switch to match their accountant's preference), and robust cybersecurity protocols, because cloud access means the firm's security posture directly affects client data.
3. Advisory Services
The highest-growth segment of accounting is advisory, and it is not a coincidence. As compliance work is automated and commoditized, the margin opportunity migrates to forward-looking services: financial planning and analysis, cash flow forecasting, M&A transaction support, performance dashboards, and business intelligence. Advisory engagements have higher margins, longer client retention, and stronger relationship depth than compliance work. Firms building advisory practices are not just diversifying revenue, they are repositioning for a market where compliance alone does not sustain competitive pricing.
4. Regulatory Scrutiny and ESG Reporting
Both IRS and SEC enforcement activity is intensifying. Simultaneously, ESG reporting frameworks, SASB, GRI, TCFD, and the SEC's climate disclosure rules, are creating new assurance requirements that accountants are well-positioned to fulfill. The Corporate Transparency Act's beneficial ownership reporting requirements under FinCEN affect hundreds of thousands of small businesses and have created a new advisory opportunity for accounting firms advising on compliance. Firms that develop ESG reporting competency and CTA advisory capability are capturing clients that compliance-only firms cannot serve.
5. Cryptocurrency and Digital Assets Accounting
FASB's 2023 ASU on fair value measurement for crypto assets is now in effect, requiring mark-to-market accounting for most digital assets rather than impairment-only treatment. This change, combined with IRS requirements to report digital asset transactions on every tax return, creates significant demand for accounting professionals with digital asset expertise. The technical requirements are non-trivial: cost basis tracking across multiple wallets and exchanges, identification of taxable events (every trade, swap, or use of crypto as payment), and compliance with the evolving IRS guidance.
Tools like CoinTracker, ZenLedger, and Ledgible address the data aggregation problem; the professional judgment layer requires trained accountants.
6. Improved Client Experience
Client expectations have shifted toward the same seamless digital experience they receive from banks and fintech platforms. Document upload portals, real-time financial dashboards, automated tax deadline reminders, and mobile-accessible reports are no longer premium features, they are table stakes. Firms competing on service quality must invest in client-facing technology: practice management platforms like Karbon and Jetpack Workflow, client portals, and reporting tools like Fathom and Power BI that make financial insights accessible to non-accountants.
7. Talent and Culture Investment
The accounting profession faces a documented talent shortage. Fewer students are sitting for the CPA exam; the 150-credit-hour requirement is increasingly cited as a deterrent; and the profession's historically conservative culture has made it less attractive to candidates from technology and analytics backgrounds. Firms that address this directly, offering genuine remote work flexibility, investing in upskilling programs, creating advancement tracks for non-CPA specialists, and fostering a culture of continuous learning and innovation, will recruit and retain the talent needed to execute on technology-enabled advisory services.
Conclusion
The future of accounting belongs to professionals and firms that combine technical accounting knowledge with technological fluency and advisory capability. AI will not replace accountants; it will replace the tasks that occupy accountants today, freeing time for the judgment-intensive, relationship-driven work that technology cannot replicate. The transition requires investment, in tools, in training, and in repositioning, but the firms making that investment now are building durable advantages over those deferring it.
Software Tools Referenced
Profitjets reports a 98% client retention rate, while expanding its use of cloud accounting, real-time reporting, and AI-powered automation to move beyond routine bookkeeping toward more data-driven financial support.
:The biggest change I’ve made is moving our team away from spending most of its time on repetitive data entry and toward using automation and cloud tools to keep financial information current. That gives us more time to review trends, identify issues early, and have meaningful conversations with clients about what their numbers actually mean for the business.
- AI/automation: QuickBooks AI, Xero, UiPath, Blue Prism (RPA), Intuit Tax Advisor, Canopy, Avalara
- Cloud accounting: QuickBooks Online, Xero, NetSuite, Zoho Books, Sage Intacct
- Digital assets: CoinTracker, ZenLedger, Ledgible
- Advisory/dashboards: Power BI, Fathom, Karbon, Jetpack Workflow
Book a free consultation and we will do more than file the paperwork.
FAQs
Will AI replace accountants?
Not wholesale, but it will replace the repetitive data-entry and report-generation tasks that currently consume much of accountants' time. Accountants who develop advisory, analytical, and client-relationship skills will see their value increase. Those who only handle routine compliance work face displacement.
What is ESG reporting and does it affect small businesses?
ESG (Environmental, Social, Governance) reporting discloses a company's impact beyond financial performance. Currently, formal ESG reporting requirements mainly apply to larger public companies. However, small businesses supplying to large corporations are increasingly required to provide ESG data as part of supply chain due diligence. Proactive ESG tracking will become increasingly important.
How should accounting firms prepare for digital asset clients?
Start by understanding the basics: the IRS treats cryptocurrency as property (not currency), meaning every transaction is a taxable event requiring cost basis tracking. Invest in specialized tools (CoinTracker, ZenLedger) and train staff on FASB's 2023 fair value measurement guidance. Clients with significant crypto holdings need specialized support that most general practitioners do not yet provide.
What is the Corporate Transparency Act and how does it affect businesses?
The CTA requires many small businesses to file beneficial ownership information (BOI) reports with FinCEN, disclosing who owns or controls the company. Most LLCs and corporations must comply. Accounting firms are increasingly advising clients on this requirement and filing on their behalf. Non-compliance carries significant civil and criminal penalties.
How are advisory services different from traditional accounting services?
Traditional services (tax prep, bookkeeping, auditing) are compliance-focused, ensuring accuracy and regulatory adherence. Advisory services are forward-looking, financial planning, growth strategy, cash flow management, M&A guidance, performance benchmarking. Advisory engagements typically have higher margins and stronger client relationships than compliance work.

Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Want an Accountant Who Advises?
Book a free consultation and we will do more than file the paperwork.