
Plenty of freelancers, consultants, and business owners pay their full tax bill on time in April and are still charged a penalty. It feels unfair. The tax was paid, so what's the penalty for? The answer is that the federal tax system is pay-as-you-go. The IRS expects tax to be paid as income is earned during the year, and paying the balance in April doesn't erase the fact that too little was paid in the earlier quarters.
W-2 employees rarely notice this, because withholding comes out of every paycheck. People with self-employment income, investment gains, rental income, or a big one-time sale don't have that built-in system. They need quarterly estimated tax payments or extra withholding to keep up, and a shortfall in any quarter can trigger the underpayment penalty.
Form 2210 is where that penalty is figured. Many people never need to file it, because they meet a safe harbor or let the IRS calculate the penalty for them.
But the form matters when your income was uneven during the year, when you had withholding timing you want credit for, or when you qualify for a waiver. In those cases, completing Form 2210 yourself can shrink the penalty or remove it entirely.
This guide explains how estimated tax works, the safe harbors that prevent the penalty, how the penalty is calculated, when you must file Form 2210, the annualized income installment method, waivers, and practical ways to stay on track.
Who Must File Form 2210?
Not everyone who underpaid owes a penalty, and not everyone who owes a penalty needs to file Form 2210 (the IRS will calculate it). You should file Form 2210 if:
- You want to use the annualized income installment method (because income is uneven through the year)
- You want to claim a waiver (unusual circumstances or retirement/disability exception)
- You are requesting a lower penalty calculation using actual withholding dates
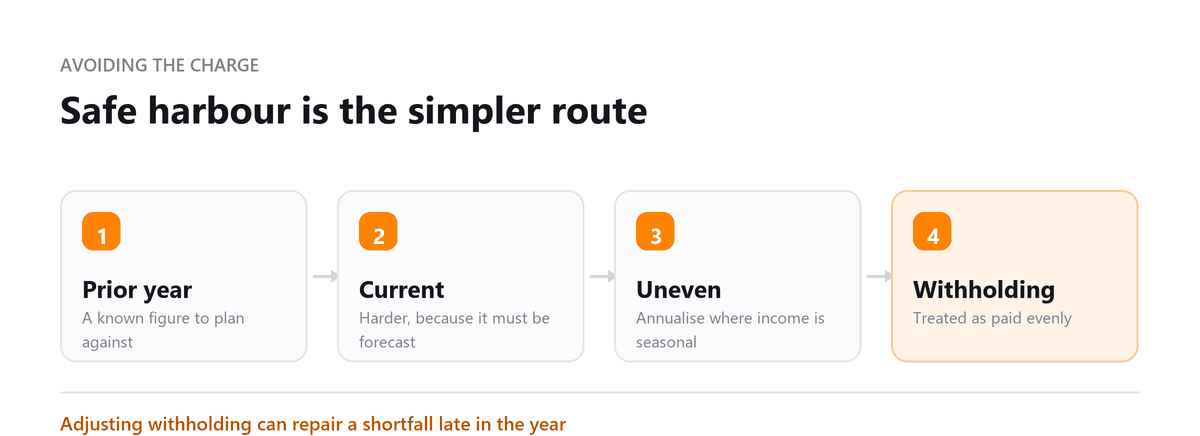
The estimated tax strategy self-employed clients overlook most is withholding. If you or your spouse have a W-2 job, or you take IRA distributions, tax withheld is treated as paid evenly throughout the year, even if it's withheld in December.
So an owner who realizes in the fall that they've underpaid can increase withholding for the last few months, and that extra amount counts toward the earlier quarters too. A fourth-quarter estimated payment only covers the fourth quarter. Used this way, withholding can wipe out penalties that an estimated payment alone would still leave behind.
Ankit Sarawagi, CPA, CA, MBA · LinkedInSafe Harbor: Avoid the Penalty Entirely
You avoid the underpayment penalty if you meet any one of these three safe harbors:
| Safe Harbor | Requirement |
|---|---|
| Tax due after withholding is less than $1,000 | Penalty does not apply |
| Prior year tax safe harbor, lower income | You paid 100% of last year's tax liability through withholding and estimated payments (AGI ≤ $150,000) |
| Prior year tax safe harbor, higher income | You paid 110% of last year's tax liability through withholding and estimated payments (AGI > $150,000) |
Quarterly Estimated Tax Due Dates
| Quarter | Income Covered | Due Date |
|---|---|---|
| Q1 | January 1, March 31 | April 15 |
| Q2 | April 1, May 31 | June 15 |
| Q3 | June 1, August 31 | September 15 |
| Q4 | September 1, December 31 | January 15 of the following year |
For TY2025: Q1 due April 15, 2025; Q2 due June 16, 2025; Q3 due September 15, 2025; Q4 due January 15, 2026.
How the Underpayment Penalty Is Calculated
The penalty is figured separately for each installment period. It applies to the amount you were short for that installment, for the number of days it remained unpaid.
The rate is the federal short-term rate plus 3 percentage points, set by the IRS each quarter. When the rate changes during the period an installment is late, each part of the period uses the rate in effect at that time.
The period generally runs from the installment due date until the earlier of the date the underpayment is paid or the original due date of the return, typically April 15.
Unlike interest on unpaid tax, the underpayment penalty isn't compounded daily. It's calculated like simple interest on each shortfall for the time it was outstanding.
Payments are applied to the earliest underpaid installment first. So a large payment made in the fourth quarter first reduces any shortfall from earlier quarters, but it doesn't reduce the penalty that already built up on those earlier shortfalls before it was paid.
Annualized Income Installment Method
If your income is uneven during the year, a large sale closed in Q3, a seasonal business with income concentrated in Q4, the regular equal-payment method may overstate your Q1/Q2 underpayment while underusing your Q3/Q4 payments. The annualized method in Schedule AI of Form 2210 calculates estimated tax requirements using actual income earned in each period, reducing or eliminating penalties from the early quarters.
Profitjets manages quarterly estimated tax planning for more than 100 self-employed and high-income clients, helping them align payments with changing income and reduce the risk of underpayment penalties.
“My consulting income was highly uneven, so the standard estimated-tax calculation made it look like I had a significant Q1 and Q2 underpayment. Profitjets used the annualized income installment method to match my estimated payments to when I actually earned the income, which eliminated an estimated $4,500 underpayment penalty for the year.”
Book a free consultation and we will set the payments up properly.
Frequently Asked Questions
How do I avoid the underpayment penalty?
You generally avoid it if you owe less than $1,000 after withholding and credits, or if your withholding and timely estimated payments cover at least 90 percent of this year's tax or 100 percent of last year's tax. If last year's adjusted gross income was more than $150,000, or $75,000 if married filing separately, you need to cover 110 percent of last year's tax.
What is the underpayment penalty rate?
The rate is the federal short-term rate plus 3 percentage points, set by the IRS each quarter. The penalty is calculated separately for each installment you underpaid, for the number of days it remained unpaid, and it isn't compounded.
Do I have to file Form 2210 if I owe a penalty?
Not always. You can let the IRS calculate the penalty and bill you. You must file Form 2210 if you're requesting a waiver, using the annualized income installment method, treating withholding as paid on the actual dates it was withheld, or in certain situations involving joint and separate returns.
What is the annualized income installment method?
It's a way to calculate required estimated payments based on the income you actually earned in each period, rather than assuming income was spread evenly across the year. It's calculated on Schedule AI of Form 2210 and can reduce or eliminate penalties for people whose income was concentrated later in the year.
Can the IRS waive the underpayment penalty?
Yes, in some cases. The penalty can be waived if the underpayment was caused by a casualty, disaster, or other unusual circumstance, or if you retired after age 62 or became disabled during the year or prior year and had reasonable cause. You request a waiver by filing Form 2210 with an explanation and supporting documents.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Hit With an Underpayment Charge?
Book a free consultation and we will set the payments up properly.