
When you work for someone else, taxes mostly take care of themselves. Money is withheld from every paycheck, a W-2 arrives in January, and the return is fairly simple. Once you run your own business, that changes. You're responsible for income tax, self-employment tax, possibly payroll taxes for employees, estimated payments throughout the year, and sometimes obligations in more than one state.
The upside is that business owners also have far more control over their tax bill. Almost any cost that's genuinely part of running the business can reduce taxable income, and the timing of purchases, payments, and elections can shift what you owe from one year to the next.
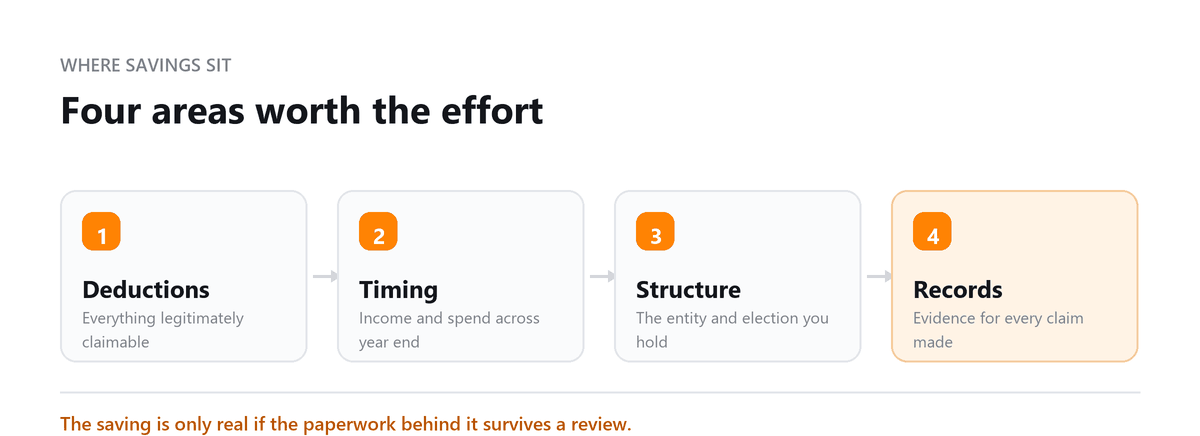
The owners who pay the least aren't using aggressive schemes. They know which expenses count, keep records that hold up, and make decisions before year-end instead of after it.
Most of the tax money small businesses lose comes from small, repeated gaps: the software subscription paid on a personal card, the mileage nobody logged, startup costs never deducted, or the quarterly payment that slipped. This guide focuses on closing those gaps.
Expert Perspective
This guide covers how business deductions work, what is and isn't deductible, commonly overlooked deductions, recordkeeping, year-end tax tips, and the mistakes that most often cost small businesses money. For the three biggest structural strategies, retirement plans, business structure, and a deeper look at deductions, see our guide to small business tax saving strategies.
The most underused deduction I see isn't anything exotic. It's the ordinary expenses owners pay personally and never bring into the books: the phone bill, a laptop bought before the business was formed, software on a personal card, business miles driven in the family car. Individually they look too small to bother with. Across a year, they often add up to thousands of dollars of deductions that were simply never claimed.
Ankit Sarawagi, CPA, CA, MBA · LinkedInHow Business Deductions Work
To be deductible, a business expense generally must be both ordinary and necessary. An ordinary expense is one that's common and accepted in your line of business. A necessary expense is one that's helpful and appropriate for the business, even if it isn't strictly essential.
A deduction lowers your taxable income, not your tax dollar for dollar. What it saves depends on your tax rate. For a sole proprietor in the 22 percent federal bracket, a $1,000 business expense typically saves about $220 in income tax, plus around $140 in self-employment tax because it also reduces business profit.
That's also why buying something just for the write-off rarely makes sense. Spending $1,000 to save roughly $360 still leaves you $640 poorer. Deductions are valuable when they capture costs the business actually needs.
What Counts as a Deductible Business Expense?
| Deductible | Not Deductible |
|---|---|
| Business meals (50%) | Personal meals |
| Business travel (100%) | Commuting to your regular workplace |
| Home office (dedicated space) | Personal portion of home expenses |
| Business vehicle use | Personal vehicle use |
| Professional development | General personal education |
| Business insurance premiums | Personal life insurance (generally) |
Commonly Overlooked Deductions
| Generally Deductible | Generally Not Deductible |
|---|
Startup and Organizational Costs
Costs you paid before the business opened, such as market research, advertising before launch, and legal fees to form an LLC or corporation, can be deducted. You can generally deduct up to $5,000 of startup costs and up to $5,000 of organizational costs in your first year of business. Each $5,000 allowance is reduced once those costs exceed $50,000, and anything left over is amortized over 15 years.
Assets You Owned Before the Business Started
A computer, desk, camera, or vehicle you already owned and then started using for the business may be depreciable. The deductible basis is generally the lower of what you paid for it or its fair market value when you began using it for business.
The Qualified Business Income Deduction
Many owners of sole proprietorships, partnerships, LLCs, and S corporations can deduct up to 20 percent of qualified business income. The deduction was scheduled to expire after 2025, but legislation passed in 2025 made it permanent. It's claimed on your personal return, you don't need to itemize to take it, and limits apply at higher incomes, particularly for service businesses.
Self-Employed Health Insurance
If you're self-employed and pay your own health insurance, premiums for you, your spouse, and dependents can generally be deducted as an adjustment to income. You can't claim it for months you were eligible for an employer-subsidized plan, including through a spouse, and the deduction can't exceed your business profit.
Half of Self-Employment Tax
You can deduct half of your self-employment tax as an adjustment to income. It lowers your income tax, not the self-employment tax itself, and it's easy to miss if you prepare your own return without software.
Bank Fees, Merchant Fees, and Interest
Credit card processing fees, payment platform fees, business bank account charges, and interest on business loans and credit cards used for business purchases are all deductible.
Business Gifts
You can deduct up to $25 per recipient per year for business gifts. Incidental costs like engraving, packaging, and shipping don't count toward that limit.
Phone, Internet, and Software
The business-use percentage of your cell phone and internet service is deductible, along with software, cloud storage, website hosting, and domain names.
Continuing Education and Memberships
Industry conferences, online courses, trade association dues, professional licenses, and publications related to your current business are all generally deductible.
Equipment: Section 179 and Bonus Depreciation
You don't always have to spread the cost of equipment over several years. Legislation passed in 2025 made two major changes for businesses buying equipment:
Section 179 expensing now allows businesses to deduct up to $2.5 million of qualifying property, adjusted for inflation, with the deduction reduced once total qualifying purchases pass a higher threshold. Section 179 can't create a loss, since the deduction is limited to your business income.
Bonus depreciation returned to 100 percent for qualifying property acquired after January 19, 2025, and there's no business income limit, so it can create or increase a loss.
For smaller purchases, the de minimis safe harbor election lets many businesses expense items costing up to $2,500 each, without tracking them as fixed assets.
Immediate expensing isn't always the best choice. If you expect to be in a higher tax bracket in future years, spreading depreciation out can sometimes save more overall. It's worth running both options.
Recordkeeping Tips That Protect Your Deductions
Keep Business and Personal Money Separate
Use a dedicated business bank account and credit card for business spending only. It makes every deduction easier to identify and far easier to support if the IRS asks questions.
Save Receipts and Note the Purpose
Keep receipts or invoices for every expense, along with a short note on the business purpose where it isn't obvious. For meals, record who attended and what was discussed.
Keep a Mileage Log
Vehicle deductions need a record of the date, destination, business purpose, and miles for each trip. Mileage tracking apps make this almost automatic.
Document Your Home Office
Measure the office and your total home, and take a few photos of the space. If you use the regular method, keep bills for rent or mortgage interest, utilities, and insurance.
Keep Records Long Enough
The general rule is to keep tax records for at least three years from the date you file. For assets and home office depreciation, keep records for as long as you own the asset, plus at least three more years.
Year-End Tax Tips
A tax planning review in October or November, while there's still time to act, is one of the most valuable habits a business owner can build. Review these points before December 31.
Project your profit. Estimate full-year income so you know roughly what bracket you're in and whether it makes sense to accelerate or defer income and expenses.
Time equipment purchases. If you need equipment in the next few months and expect a strong year, buying and placing it in service before year-end can bring the deduction into this year.
Fund or open a retirement plan. Some plans, like a Solo 401(k), need to be established by year-end for certain contributions to count. Others, like a SEP-IRA, can be funded up to the filing deadline.
Pay deductible expenses. For cash-basis businesses, paying bills and stocking up on needed supplies before year-end can pull deductions into the current year. Don't prepay far into the future, since many prepaid expenses must still be deducted over the period they cover.
Review your business structure. If your profit has grown significantly, model whether an S corporation election makes sense for next year, before the March 15 election deadline for calendar-year businesses.
Collect contractor information. Gather W-9s from anyone you've paid during the year so you're ready to issue Forms 1099 in January.
Common Small Business Tax Mistakes
| Mistake | Why It Costs You | How to Avoid It |
|---|---|---|
| Mixing personal and business spending | Deductions get missed and the ones you claim are harder to support | Use separate accounts and cards |
| Missing quarterly estimated payments | Underpayment penalties, even if you pay in full at filing | Pay quarterly, using a safe harbor if income varies |
| Not reporting all income, including cash and payment app receipts | Notices, back taxes, and penalties when income doesn't match IRS records | Record every sale and reconcile deposits monthly |
| Deducting 100% of meals or claiming entertainment | Disallowed deductions and possible penalties | Deduct business meals at 50% and leave out entertainment |
| No mileage log | Vehicle deductions can be disallowed entirely | Track trips as you go |
| Classifying employees as contractors | Back payroll taxes, penalties, and interest | Review how much control you have over how, when, and where work is done |
| Forgetting Forms 1099 | Per-form penalties for late or missing information returns | Collect W-9s up front and file by the January deadline |
| Electing S corporation status too early | Payroll and compliance costs outweigh the tax savings | Wait until profit is consistently in the low six figures, and model it first |
Conclusion
Small business taxes don't reward complexity. They reward consistency. Know the difference between deductible and personal expenses, capture the ones owners most often miss, keep records that stand on their own, and review your numbers before the year ends instead of after. Pair those habits with the bigger decisions, like the right retirement plan and business structure, and your tax bill will reflect how the business actually operates rather than whatever happened to make it into the books.
Book a free consultation and we will review the year before it closes.
Frequently Asked Questions
How much can a small business deduct?
There's no overall cap on ordinary and necessary business expenses. Specific limits apply to certain items, including business meals at 50 percent, business gifts at $25 per recipient, startup and organizational costs at $5,000 each in the first year, the home office deduction, and Section 179 expensing, which is limited to business income.
How can a small business owner avoid overpaying taxes?
Claim every legitimate business expense, deduct half of your self-employment tax, take the qualified business income deduction if you're eligible, use a retirement plan, choose the right equipment depreciation method, and review your business structure as profit grows. Good bookkeeping underpins all of it.
What is the QBI deduction, and is it still available?
The qualified business income deduction lets eligible owners of pass-through businesses deduct up to 20 percent of qualified business income. It was set to expire after 2025, but 2025 legislation made it permanent. Limits apply at higher income levels, especially for professional service businesses.
Can I deduct expenses I paid before my business started making money?
Often, yes. Costs incurred before opening, such as research, pre-launch marketing, and legal fees to form the business, can generally be deducted up to $5,000 each for startup and organizational costs in the first year, with the rest amortized over 15 years. Once the business is operating, ordinary expenses are deductible even if it hasn't turned a profit yet.
Do I need receipts for every business expense?
You need records that show the amount, date, and business purpose. For meals, travel, gifts, and vehicle expenses, the IRS generally expects receipts for expenses of $75 or more and for all lodging, along with notes on the business purpose. Keeping receipts for everything is the safest habit.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Savings Found for You?
Book a free consultation and we will review the year before it closes.