
What Is a Bank Reconciliation?
Bank reconciliation is the process of aligning a business's internal financial records with its bank statements to confirm that every transaction has been recorded accurately and to identify any discrepancies between the two sources. In practice, this means comparing your cash ledger, maintained in your accounting software or manually, against the transactions your bank has processed during the same period. Differences may arise from outstanding checks not yet cleared, deposits in transit, bank fees not yet recorded in your books, or outright errors on either side.
The output is a reconciliation statement that shows the starting balances, all adjustments, and a final reconciled balance that should match across both records. For small businesses, this is typically performed monthly, although businesses with high transaction volumes may reconcile weekly.
The most common issue I see in small business books is outstanding checks that are months old. Either the check was lost and needs to be reissued, or someone cashed it without it clearing your records. Regular reconciliation catches both situations before they become costly problems.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhy Does Bank Reconciliation Matter for Small Businesses?
Bank reconciliation is not a bureaucratic requirement, it is a practical safeguard with four direct benefits for small businesses. First, it detects fraudulent activity: unauthorized withdrawals, duplicate charges, or payments to unknown vendors become visible the moment you compare your internal records to the bank statement. Second, it supports tax and regulatory compliance by ensuring the numbers you report reflect reality. Third, it clarifies your actual cash position, which is especially important when your books may include outstanding items that have not yet cleared.
Fourth, it ensures your financial statements are built on accurate data, which makes tax preparation faster and less error-prone.
What Is the Primary Purpose?
The primary purpose of bank reconciliation is to verify that the cash balance shown in your business's accounting records matches the actual cash balance held in your bank account at the end of a given period. When the two balances differ, as they frequently do due to timing differences, the reconciliation process explains every difference and ensures both records are brought into agreement before financial statements are finalized.
Step-by-Step Guide, How to Do Bank Reconciliation
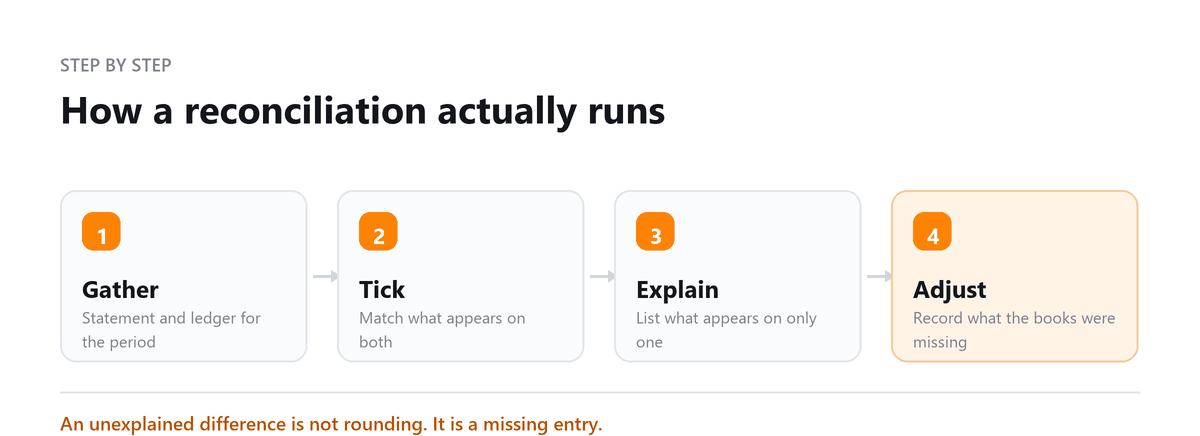
Bank reconciliation follows a consistent six-step process regardless of the size of the business or the accounting tools used.
Step 1: Gather Your Documents
Before you begin, collect three things: your bank statement for the period you are reconciling, your internal cash ledger or accounting register showing all recorded transactions for the same period, and a list of any outstanding checks or deposits in transit from the previous period. Without all three, you cannot complete a thorough reconciliation.
Step 2: Compare Opening Balances
Verify that the closing balance from your previous reconciliation matches the opening balance on your current bank statement and your current accounting records. If these do not match, the discrepancy must be resolved before proceeding, otherwise errors from the prior period will compound.
Step 3: Match Transactions
Go through every line item on your bank statement and match each deposit, payment, and fee against your internal records. Mark off each item as it is confirmed. Any item that appears in one source but not the other becomes a reconciling item requiring investigation.
Step 4: Adjust Your Records
After matching, make the necessary adjustments. Add any bank fees, interest charges, or bank-initiated transactions that appear on the statement but are missing from your books. Remove items from your book balance that represent checks written but not yet cleared, or deposits recorded but not yet received by the bank (deposits in transit).
Step 5: Calculate the Ending Balance
Adjust both your book balance and your bank statement balance for the outstanding items. The adjusted book balance should equal the adjusted bank balance. If they match, the reconciliation is complete. If they do not, continue reviewing for errors, duplicate entries, or missing transactions.
Step 6: Review and Finalize
Document any discrepancies with clear explanations for the record. Archive the completed reconciliation statement alongside the bank statement for that period. Most accounting software allows you to mark the reconciliation as complete, locking those periods against accidental changes.
Bank Reconciliation Example
Consider a simple example. Your accounting records show a book balance of $12,450 at month end. Your bank statement shows a balance of $12,750. The difference of $300 is explained by an outstanding check you wrote that has not yet cleared the bank. To reconcile: your adjusted book balance remains $12,450 (the check is already recorded in your books). Your adjusted bank balance is $12,750 minus the $300 outstanding check = $12,450. Both sides now agree, and the reconciliation is complete.
Bank Reconciliation Statement
A bank reconciliation statement is the formal document that summarizes the entire reconciliation process. It is used both as an internal control record and as supporting documentation for audits or tax filings. The statement captures every adjustment made to arrive at the reconciled balance and provides a clear audit trail.
What Should a Bank Reconciliation Statement Include?
A complete bank reconciliation statement should include the business name and account details, the reconciliation period start and end dates, the opening book balance and opening bank balance, a list of all additions (deposits in transit, interest earned) with individual amounts, a list of all deductions (outstanding checks, bank fees not in books) with individual amounts, the adjusted book balance, the adjusted bank balance, and a confirmation that the two adjusted balances are equal. Any remaining unexplained differences should be flagged for follow-up.
Challenges of Bank Reconciliation for Small Businesses
Small businesses face several recurring reconciliation challenges. Unrecorded bank fees, particularly for wire transfers, overdrafts, or account maintenance, are frequently missed because they appear on the statement without prior notice. Outstanding checks that age beyond 90 days create complications: they may represent lost checks that need to be voided and reissued, or payments that cleared without being matched in the books. Timing differences between when a transaction is recorded internally and when it clears the bank are normal but require careful tracking.
High transaction volumes during busy periods can make manual matching impractical without accounting software.
How Profitjets Can Help
Profitjets provides outsourced bookkeeping services that include monthly bank reconciliation as a core deliverable. Our team handles the matching, adjusting, and statement preparation so business owners receive a reconciled set of books within days of month end, without spending hours on the process themselves. For businesses that have fallen behind on reconciliation, we also offer catch-up services to bring books current from any prior period.
Conclusion
Bank reconciliation is one of the simplest and most effective financial controls a small business can implement. Done consistently, monthly at minimum, it keeps your cash records accurate, surfaces discrepancies before they grow, and ensures every financial statement you produce is built on verified data. Whether you reconcile manually, through software, or by outsourcing to a bookkeeping partner, the discipline of regular reconciliation pays for itself many times over in errors caught and fraud prevented.
Book a free consultation and we will get every account matched.
Frequently Asked Questions
How long does bank reconciliation take?
For a small business with under 200 monthly transactions, reconciliation typically takes 30 to 90 minutes when done monthly. Businesses that reconcile quarterly find it takes 3 to 5 hours because discrepancies have had more time to compound.
What if my bank reconciliation never balances?
Start by checking for transposition errors (digits reversed), duplicate entries, or missing transactions. Run the reconciliation in accounting software to flag unmatched items automatically. If you still can't balance, consider engaging an outsourced bookkeeper to audit the discrepancy.
Can I outsource my bank reconciliation?
Yes, and many small businesses do. Outsourced bookkeeping firms handle reconciliation as a standard service, typically delivering a reconciled statement within 5 to 7 business days after month end. It removes the time burden and adds an independent check.
How far back can I reconcile if I've fallen behind?
You can reconcile as far back as you have records. Start from your last confirmed reconciled balance and work forward month by month. This is called catch-up reconciliation and can take several weeks for multiple years of backlog.
Does bank reconciliation work differently for businesses with multiple accounts?
Each account must be reconciled separately. Businesses with multiple checking, savings, or payroll accounts run the same process for each account, some accounting software supports multi-account reconciliation views to manage them efficiently.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Reconciliation Not Balancing?
Book a free consultation and we will get every account matched.