
Small businesses run for years on a bank balance and a folder of receipts. Money comes in, bills go out, and as long as the account doesn't hit zero, things seem fine. Then a lender asks for a balance sheet, a tax notice arrives, or the owner tries to work out whether a new hire is affordable, and it turns out nobody can say how profitable the business actually is.
That's the gap accounting fills. Accounting is the process of recording a business's financial transactions, organizing them in a consistent structure, and turning them into reports that show how the business is performing and what it owns and owes. Every sale, bill, payroll run, and loan payment eventually becomes part of the financial statements that owners, lenders, investors, and tax authorities rely on.
Good accounting isn't just about staying compliant. It's what lets you price with confidence, spot a cash shortfall before it arrives, apply for financing with numbers that hold up, and make decisions based on what's actually happening in the business rather than a feeling about it.
This guide covers what accounting is, how it works, why it matters, the main types of accounting, the accounting cycle, cash vs accrual accounting, key ratios, how accounting differs from bookkeeping, and how to choose accounting software.
What is Accounting?
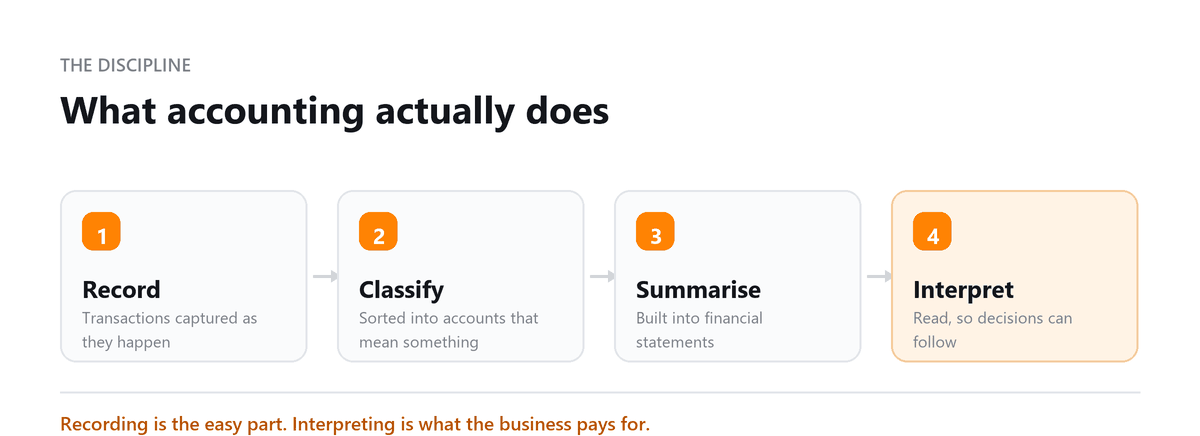
Accounting is the systematic process of recording, analyzing, summarizing, and reporting financial transactions of a business or individual. It provides a clear picture of financial condition at any given moment, enabling business owners, investors, and regulators to make informed decisions. At its core, accounting answers a deceptively simple question: what is the true financial state of this organization?
Far more than data entry, accounting transforms raw transaction records into meaningful financial intelligence. Every purchase, sale, payroll run, and loan repayment flows through an accounting system and eventually surfaces as a number in a financial statement that stakeholders rely on.
Most business owners only look closely at their numbers at tax time, and by then the year is over and nothing can change. Accounting is really a monthly habit. When the books are closed and reviewed every month, you can see margins slipping, costs creeping up, or a customer paying late while there's still time to act. The businesses I've seen grow most steadily aren't the ones with the fanciest software. They're the ones where someone looks at a clean set of monthly financials and asks what they mean.
Ankit Sarawagi, CPA, CA, MBA · LinkedInHistory of Accounting
Accounting is one of humanity's oldest professions. The Babylonians and Egyptians used clay tablets and papyrus to record grain stores and trade transactions as far back as 2600 BCE. Ancient Rome maintained detailed public financial records for government expenditure.
The pivotal development came in 15th-century medieval Italy, where mathematician and friar Luca Pacioli published Summa de Arithmetica in 1494, documenting the double-entry bookkeeping system that remains the foundation of modern accounting. The industrial revolution drove demand for more sophisticated cost tracking, and the 20th century brought regulatory frameworks, GAAP in the United States, IFRS internationally, that standardized how financial information is reported and audited.
How Does Accounting Work?
Accounting follows a logical sequence. First, transactions occur, a sale is made, a bill is paid, a loan is drawn. Each transaction is recorded in an accounting system using journal entries that capture the date, accounts affected, amounts, and a description. These entries are then posted to the general ledger, which organizes every transaction by account type.
At period end, monthly, quarterly, or annually, account balances are extracted and formatted into financial statements: the income statement showing revenue and expenses, the balance sheet showing assets and liabilities, and the cash flow statement showing actual cash movement. Management and external stakeholders then analyze these statements to assess performance and inform decisions.
Importance of Accounting
Accounting underpins nearly every critical business function:
- Financial transparency: Accurate records let owners and investors understand exactly where money comes from and where it goes.
- Tax compliance: Properly maintained books are the foundation of accurate, defensible tax filings that minimize the risk of audits and penalties.
- Funding acquisition: Banks and investors require audited or reviewed financial statements before committing capital. Weak accounting is one of the leading reasons loan applications are denied.
- Performance measurement: Comparing revenue, margins, and expenses over time reveals whether strategy is working and where adjustments are needed.
- Informed decisions: Pricing changes, hiring decisions, expansion plans, all are better made with accurate financial data than gut instinct.
Types of Accounting
Modern accounting encompasses several specialized disciplines, each serving a distinct purpose:
- Financial Accounting: Produces standardized financial statements for external parties, investors, lenders, regulators. Governed by GAAP or IFRS.
- Management Accounting: Generates internal reports, budgets, forecasts, variance analyses, to support leadership decisions.
- Tax Accounting: Focuses on compliance with tax law, accurate filing, and identifying legitimate deductions and credits.
- Cost Accounting: Analyses production and operational costs to identify inefficiencies and optimize pricing.
- Auditing: The independent examination of financial records to verify accuracy and compliance. Internal auditors work inside organizations; external auditors provide third-party assurance.
What is the Accounting Cycle?
The accounting cycle is the repeating process through which financial transactions are recorded, processed, and reported each accounting period. The seven core steps are:
- 1. Identify transactions: Recognize financial events, sales, purchases, payments, that need to be recorded.
- 2. Record in journal: Create chronological journal entries using the double-entry system.
- 3. Post to ledger: Transfer journal entries to the relevant accounts in the general ledger.
- 4. Prepare trial balance: List all account balances to verify total debits equal total credits.
- 5. Adjusting entries: Record period-end accruals, deferrals, and depreciation not captured in daily transactions.
- 6. Financial statements: Compile the income statement, balance sheet, and cash flow statement.
- 7. Close books: Zero out temporary revenue and expense accounts and transfer net income to retained earnings, resetting for the next period.
What are Accounting Ratios?
Accounting ratios are calculated from financial statement figures to evaluate business performance and financial health. The main categories include:
- Liquidity ratios (e.g., current ratio, quick ratio): Measure ability to meet short-term obligations.
- Solvency ratios (e.g., debt-to-equity): Assess long-term financial stability and leverage.
- Profitability ratios (e.g., net profit margin, return on equity): Gauge how efficiently the business generates profit.
- Efficiency ratios (e.g., inventory turnover, receivables days): Evaluate how well assets and resources are being utilized.
How Does Accounting Differ from Bookkeeping?
Bookkeeping and accounting are related but distinct disciplines. Bookkeeping is the mechanical process of recording every financial transaction, entering invoices, reconciling bank statements, categorizing expenses. It is the essential raw-data layer.
Accounting builds on those records. An accountant analyzes the data, prepares financial statements, manages tax compliance, advises on financial strategy, and interprets what the numbers mean for the business. A good bookkeeper keeps the engine running; a good accountant tells you where to drive.
Best Accounting Software of 2026
Choosing the right accounting software is one of the most consequential decisions a small business owner makes. The right tool automates routine data entry, reduces errors, and provides real-time financial visibility. Here are the leading options for 2026:
| Software | Best For | Starting Price |
|---|---|---|
| QuickBooks Online | Small to mid-size businesses | $38/month |
| Xero | Growing businesses, multi-user | $25/month |
| FreshBooks | Freelancers & service businesses | $23/month |
| Zoho Books | Budget-conscious SMBs | $20/month |
| Wave | Startups & solopreneurs | Free |
From the Profitjets Team
Profitjets clients who adopt regular accounting reviews report more consistent cash-flow visibility, giving business owners a clearer view of upcoming expenses, available cash, and financial performance throughout the year.
In my experience working with small business owners, the biggest turning point is when they move from reactive to proactive accounting. Once the numbers are reviewed consistently, we can spot cash-flow pressure, unusual expenses, and changes in profitability early enough to act rather than simply explain what happened after the month has ended.
Conclusion
Accounting is not just a compliance requirement, it is the information infrastructure of a well-run business. Whether you are a solopreneur tracking cash flow or a growing company preparing for investment, maintaining accurate, timely accounting records is the foundation everything else is built on. The right accounting partner does more than keep your books clean; they turn your financial data into a strategic asset.
Book a free consultation and we will tell you what your business actually needs.
Frequently Asked Questions
Do small businesses need formal accounting, or is bookkeeping enough?
Bookkeeping keeps your records accurate, but accounting turns those records into financial statements, tax returns, and decisions. If you want to understand your true margins, plan for growth, or apply for financing, you'll need more than bookkeeping alone, even as a small business.
What's the difference between an accountant and a bookkeeper?
A bookkeeper records and organizes daily transactions and reconciles accounts. An accountant reviews those records, makes adjusting entries, prepares financial statements and tax returns, and advises on financial decisions. Many small businesses use both, often through an outsourced provider.
How often should I review my accounts?
At least monthly. A monthly close and review catches errors early, gives you a current view of cash and profit, and makes year-end tax preparation much simpler.
Can accounting software replace an accountant?
Software automates data entry, bank reconciliation, and standard reports, but it can't make judgment calls on tax planning, compliance, or strategy, and it only reports what's entered correctly. It works best as a tool that makes an accountant or bookkeeper more efficient.
Should a new small business use cash or accrual accounting?
Many new small businesses start on the cash basis because it's simpler. Accrual accounting gives a more accurate picture of profitability and is usually expected by lenders and investors. For taxes, most small businesses can use the cash method, while larger C corporations and certain partnerships with average annual gross receipts above an inflation-adjusted threshold must use the accrual method.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Accounting Handled Properly?
Book a free consultation and we will tell you what your business actually needs.