
In business management when sales reports show a record-breaking quarter, the accountant reports profits, and the owner faces the prospect of their bank account being empty.
This happens because gross revenue and cash flow statements represent different realties, namely, the former measures sales at the point of realization, while the latter records inflows and outflows of cash at the point of payment. Thus, the gap between the two, which represents a company’s outstanding liabilities and assets, may engulf even the most profitable revenues.
The ability to identify the reasons for the disconnect between total sales and cash inflows determines whether a company is prepared to withstand the financial storm. For businesses that seek to scale their operations, this factor accounts for the difference between a well-managed growth spurt and a cash flow disaster.
The scenario where a business with strong revenue runs out of cash almost always follows the same pattern. It lands bigger customers on longer payment terms, has to pay staff and suppliers up front to deliver the work, and grows faster than it collects. The early warning sign is nearly always the same too: receivables growing faster than revenue.
Sales are up 20%, but unpaid invoices are up 50%. When that shows up in the numbers, the cash crunch is usually two or three months away, which is still enough time to tighten terms, chase collections, or arrange a credit line before it arrives.
Abhinav Gupta, CPA, CA, MBA · LinkedInGross revenue and cash flow are not the same number, and confusing them is one of the most dangerous financial mistakes a small business owner can make. A business can report high revenue and still run out of cash. Understanding why requires understanding the difference between when revenue is recognised and when cash actually arrives.
What Is Gross Revenue?
Gross revenue (also called turnover or top-line revenue) is the total value of goods sold or services delivered during a period, before any deductions. It is recognised when earned (under accrual accounting), not when cash is received.
- A $50,000 project delivered in March is March revenue, even if the client pays in June
- A $200/month SaaS subscription starting January 1 is January revenue, even if billed quarterly in advance
- Gross revenue does not deduct returns, refunds, or discounts, net revenue does
What Is Cash Flow?
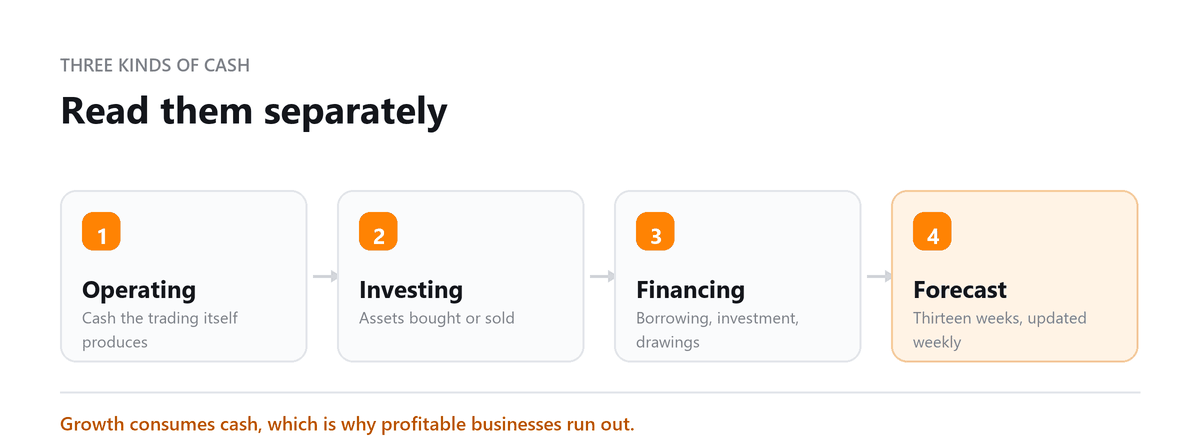
Cash flow is the actual movement of cash into and out of your bank account during a period. It does not care when revenue was earned, only when cash was received. The cash flow statement has three sections:
| Section | What It Covers | Example |
|---|---|---|
| Operating Cash Flow | Cash from core business operations, collections from customers minus payments to suppliers and employees | +$45,000 collected from clients; −$30,000 wages paid |
| Investing Cash Flow | Cash from buying/selling long-term assets | −$20,000 new laptop and equipment purchased |
| Financing Cash Flow | Cash from debt and equity transactions | +$50,000 bank loan received; −$5,000 loan repayment |
Why Gross Revenue and Cash Flow Differ: A Worked Example
A consulting firm with 3 active projects in Q1:
| Project | Revenue Earned (Q1) | Cash Received (Q1) | Difference |
|---|---|---|---|
| Client A, paid in advance | $30,000 | $30,000 | $0 |
| Client B, invoiced March 1, pays April 15 | $45,000 | $0 | −$45,000 |
| Client C, 50% deposit, balance on completion (April) | $20,000 | $10,000 | −$10,000 |
| TOTALS | $95,000 revenue | $40,000 cash received | −$55,000 gap |
The business reports $95,000 in Q1 revenue but only $40,000 in cash received, a $55,000 gap sitting in accounts receivable. If the business has $60,000 in Q1 expenses, it is cash-flow negative despite profitable revenue.
The Accrual vs Cash Accounting Difference
| Accrual Accounting | Cash Accounting | |
|---|---|---|
| Revenue timing | Recognised when earned (when delivered) | Recognised when cash is received |
| Expense timing | Recognised when incurred (when committed) | Recognised when cash is paid |
| Gross revenue figure | Includes uncollected invoices | Only includes cash actually received |
| Cash flow figure | Same in both systems (cash is cash) | Same in both systems |
| Who uses it | Most businesses above a small threshold; required for tax in many jurisdictions | Very small businesses; sole traders in some jurisdictions |
Why This Matters for Your Business
For US federal tax purposes, many small businesses can use the cash method if they're below a gross receipts threshold, while larger businesses and some entity types generally must use accrual.
- Profitable businesses run out of cash. Revenue on paper doesn't pay wages or rent until customers actually pay.
- Taxes may be due before cash arrives. Businesses using the accrual method for tax can owe tax on income they haven't collected yet.
- Growth ties up cash. A fast-growing business keeps paying to deliver more work while waiting on last month's invoices, so its cash can fall even as sales rise.
- Lenders look at both. Revenue shows the scale of the business. Operating cash flow shows whether it can make loan payments.
How to Close the Gap
The basis you use for tax and the basis you use for management reporting don't have to be the same.
- Invoice immediately and follow up as soon as an invoice becomes overdue.
- Take deposits or milestone payments on large projects.
- Match your payment terms with suppliers to the terms you give customers where possible.
- Build a rolling 13-week cash forecast so shortfalls appear weeks in advance.
- Set up a line of credit before you need it, not during a shortfall.
- Track receivables growth against revenue growth every month.
CLIENT QUOTE:
We were bringing in strong revenue every month, but somehow we were still running short on cash. Profitjets reviewed our receivables aging and found that a large share of our sales was sitting in overdue invoices rather than in the bank. We introduced scheduled follow-ups, clearer payment terms, and weekly AR reviews, which made collections much more predictable.
Book a free consultation and we will build the forecast with you.
FAQs
Is high revenue always good for cash flow?
Not necessarily. Growing revenue can strain cash when customers pay slowly, payment terms are long, or the business has to pay for staff, materials, or inventory before it's paid. Rapid growth is one of the most common causes of cash shortages in otherwise profitable businesses.
Which matters more, revenue or cash flow?
In the short term, cash flow, because the business pays its bills with cash. Over the long term, revenue and profit determine whether the business model works. Both matter, but if you're only watching one number week to week, watch cash.
Do I owe tax on revenue I haven't been paid for?
It depends on your tax accounting method. Businesses using the accrual method generally include revenue when it's earned, so they can owe tax before collecting. Businesses using the cash method generally include it when it's received. Your CPA can confirm which method applies to your business.
Why is my bank balance falling if the business is profitable?
Common reasons include customers paying slowly, inventory purchases, equipment bought with cash, loan principal repayments, owner distributions, and tax payments. None of these reduce profit the way they reduce cash. Comparing your balance sheet month to month shows which one is responsible.
How far ahead should I forecast cash?
A rolling 13-week forecast works well for most small businesses. It's far enough ahead to spot a shortfall and short enough to stay accurate. Update it weekly with actual receipts and payments, and pair it with a longer monthly forecast for planning.

Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Profitable but Short of Cash?
Book a free consultation and we will build the forecast with you.