
Most accounts payable forecasts paint a picture of an AP function that only big enterprises could afford to adopt while small companies would have to wait to adopt. As you read about touchless processing and autonomous finance functions, you can hardly believe it’s the same universe where invoices come into three inboxes and get coded by one person between other priorities.
The question is not what technology will bring to the finance function but what changes in finance functions will actually ripple through the operations of a ten-person company in the next two to three years versus enterprise features that have no reason to become commonplace soon.
Some of these trends have already penetrated the small business space and either become routine or are ready to become routine. The software for automating AP used to be a five-figure investment, but now it can be a monthly subscription that pays for itself thirty times over, and many accounting platforms have integrated most of the features that used to be available as separate niche products.
Real-time payments will matter, but not for the reason it's usually pitched. The pitch is speed. What actually changes for a small business is that payment timing becomes a decision you make on the day rather than a batch you set up on Tuesday and most finance teams have no process for making that decision, because they've never had to. The technology will arrive well before the discipline does.
Ankit Sagatani, MBA, B.Com · LinkedInWhat Is Accounts Payable?
Accounts payable (AP) is the function responsible for managing a business's outgoing payments to suppliers, receiving invoices, verifying them, obtaining approvals, and executing payments within agreed terms. AP sits at the intersection of cash flow management, supplier relationships, and internal financial controls.
Accounts payable is undergoing its most significant transformation in decades. Manual invoice processing, paper cheques, and email approval chains are being replaced by AI-powered automation, real-time payments, and fully digital supplier ecosystems. This guide covers the key trends reshaping AP and what small business finance teams should be doing now to prepare.
Trends Shaping the Future of AP
Some trends are already affecting small businesses indirectly, as enterprise clients require e-invoicing from their suppliers whether legislators request it or not. And some of them will remain distant goals for the foreseeable future, and there is no need to waste time and money on them yet.
1. AI-Powered Invoice Processing
Artificial intelligence is replacing OCR-only data extraction with context-aware processing that can read unstructured invoice formats, flag exceptions automatically, and learn from corrections over time. In 2026, leading AP platforms can process straight-through (no human touch) for 70-85% of routine invoices: routing only exceptions to human review.
2. Real-Time Payments
The FedNow instant payment network (launched July 2023) and the Clearing House RTP network enable real-time, 24/7 B2B payments: funds available in seconds rather than 1-3 business days for ACH. As bank participation grows, AP teams will shift from batch payment runs to on-demand payment execution, improving supplier relationships and enabling dynamic discounting programmes.
3. E-Invoicing Mandates
Mandatory B2B e-invoicing is live or phasing in across a number of jurisdictions, India's GST e-invoice system, Italy, France, Germany among them, each on its own schedule.
The US has no federal mandate. That's not the reason small businesses here should care. The reason is that large enterprise customers are increasingly requiring e-invoicing from their supplier networks regardless of what the law says, which means if you sell to enterprise, the requirement reaches you through a procurement contract rather than through legislation. Being unable to comply is a reason to lose the account.
4. Dynamic Discounting
Instead of fixed 2/10 Net 30 terms, dynamic discounting platforms let a buyer with spare cash offer early payment at a rate that scales with how early it is, pay on day four, get more off than paying on day nine.
This is the one I'd tell most readers of this page to ignore for now. It works when you have consistent surplus cash, meaningful invoice volume, and suppliers already on a platform that supports it. Very few businesses under roughly $10M revenue have all three, and the ones that do usually get most of the same benefit from simply being organised enough to hit standard 2/10 windows, worth about 37% annualised, and available today with no platform at all. Revisit it when your approval cycle is reliably under a week.
5. AP and ERP Integration
Standalone AP automation tools are being replaced by AP modules embedded directly in ERP and accounting platforms (QuickBooks, Xero, NetSuite, SAP). This eliminates the data silos between AP automation and the general ledger, invoices, payments, and GL entries stay in sync automatically without manual export/import.
How AP Automation Works
A modern AP automation workflow:
| Stage | What Happens | Human Involvement |
|---|---|---|
| Invoice receipt | Invoices arrive via email, supplier portal, or EDI, all routed to a single inbox | None |
| Data extraction | AI reads the invoice and extracts vendor, date, amount, line items, PO number | None (exceptions flagged) |
| Three-way match | System matches invoice to PO and goods receipt, approves or flags mismatches | Only for exceptions |
| Approval routing | Invoice routes to the correct approver based on amount and department rules | Approver clicks Approve/Reject |
| Payment scheduling | Approved invoices scheduled for payment on the optimal date | Finance reviews batch |
| Payment execution | ACH, wire, or virtual card payment executed automatically | None (exceptions reviewed) |
| GL posting | Payment posted to the correct accounts in the accounting system | None |
How AP Automation Benefits Small Businesses
- Processing speed: 3-7 days vs 15+ days manually
- Cost reduction: $2-$8 per invoice vs $12-$30 manually
- Error rate: <1% vs 3-5% manually
- Fraud prevention: built-in duplicate detection and approval controls
- Scalability: handles 10x invoice volume without additional headcount
Book a free consultation and we will get the data ready first.
Frequently Asked Questions
Will AI replace AP teams entirely?
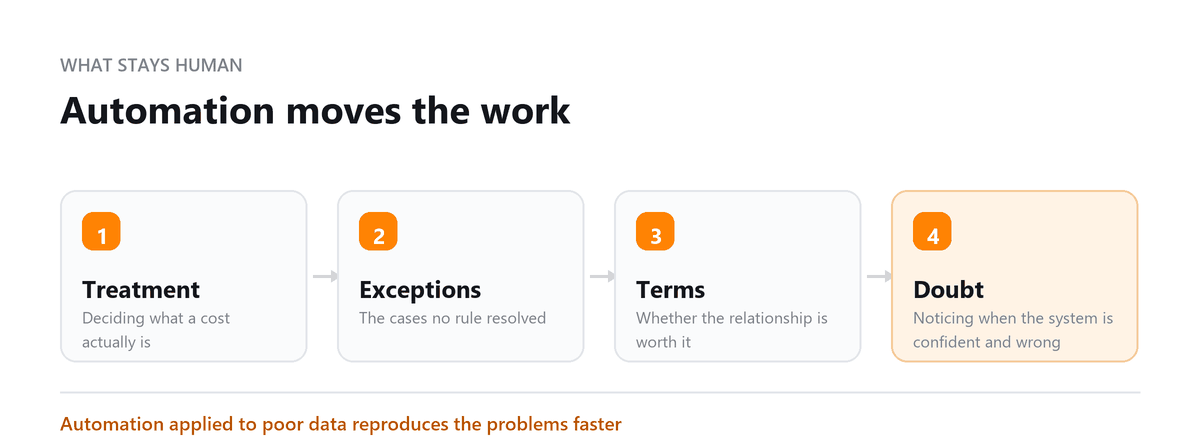
No, though the job changes substantially. AI takes over data entry, matching, routing and exception flagging. What's left for people is resolving the exceptions, managing supplier relationships, deciding payment timing against cash position, and keeping vendor data clean which is more skilled work than what it replaces.
What's the best AP automation tool for a small business?
If you're on QuickBooks, BILL integrates closely and covers both AP and AR. Xero users typically pair Dext or Hubdoc for capture with Xero's native AP features. At higher volume or with international payments, Stampli and Tipalti offer more workflow depth. Run a trial with your own messy invoices rather than clean samples, routing and exception handling only reveal themselves on real data.
How soon should a small business move to AP automation?
Volume is the usual trigger, somewhere around 20 to 30 invoices a month. But the better signal is exception rate: if more than one invoice in twenty needs someone to intervene, you have a process problem that automation will accelerate rather than solve. Fix intake and vendor data first, then automate.
Does e-invoicing affect US small businesses if there's no mandate?
Yes, through customers rather than regulators. Enterprise buyers increasingly require e-invoicing from suppliers as a contract condition, and procurement teams don't make exceptions for small vendors. If enterprise customers are part of your growth plan, confirm what formats they'll require before it becomes a condition of renewal.
Is real-time payment worth adopting now?
Adopt it when your bank supports it and your suppliers can receive it, which is increasingly both. The caution is behavioural rather than technical: when every payment can go instantly, it becomes very easy to pay everything the moment it's approved, which quietly gives away all the working capital benefit of your agreed terms. Decide your payment timing policy before you turn on instant settlement, not after.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Thinking About Automating?
Book a free consultation and we will get the data ready first.