
Small business owners discover accumulated depreciation for the first time when things don't add up. The balance sheet shows the delivery van at $30,000, but they paid $60,000 for it, or the tax return shows a large equipment deduction this year, but the books only show a little depreciation expense. They all add up correctly.
Depreciation spreads the cost of a long-lived asset, such as equipment, vehicles, furniture, etc., out over the number of years the asset is used, rather than expensing the entire purchase in the year it was bought. Accumulated depreciation is the total of this expense to date on the asset since its purchase. On the balance sheet this amount is deducted from the asset's cost, to show how much of the asset's original value has already been used.
Getting a handle on accumulation depreciation makes reading balance sheets with equipment and vehicles on them a lot simpler, and makes the difference between the books' entries and the tax return entries a lot more understandable.
Accumulated depreciation is the total amount of depreciation expense recorded against a fixed asset from the date of purchase to the current balance sheet date. It appears on the balance sheet as a contra-asset: a negative figure that reduces the gross value of the asset to its net book value.
Understanding it is essential for reading any balance sheet that includes property, plant, or equipment.
What Is Depreciation?
Depreciation is the systematic allocation of an asset's cost over its useful life. Rather than expensing the full cost of a machine or vehicle in the year of purchase, depreciation spreads the cost across the years the asset is expected to generate revenue. This matches expenses to the periods they benefit is a core principle of accrual accounting.
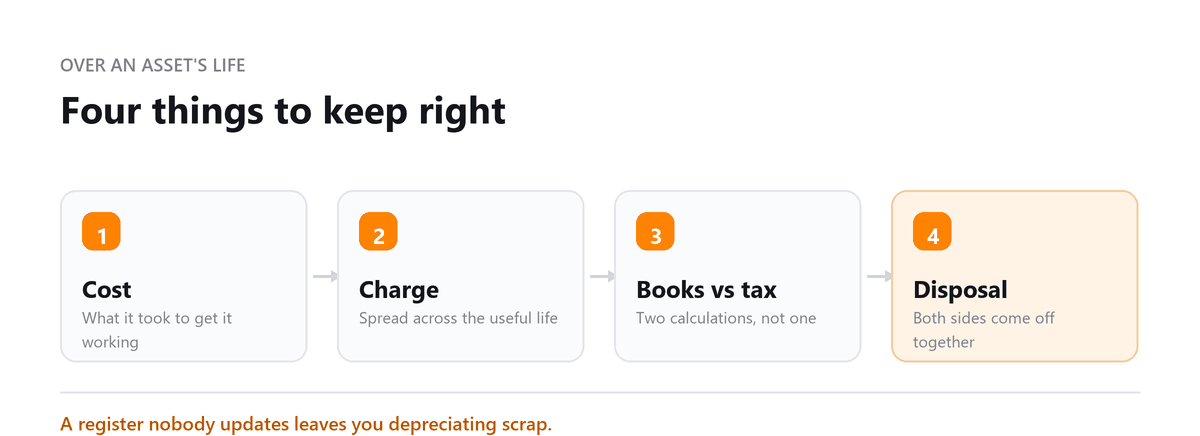
The depreciation issue I run into most isn't choosing the wrong method. It's asset records that no one has maintained. Equipment gets bought and expensed in full because the owner assumed a large tax write-off, sold vehicles are never removed from the books, and nobody can match the balance sheet to the assets the business actually owns.
The tax return may be right while the books overstate or understate assets by tens of thousands of dollars. A simple fixed asset register, updated every time something is bought or sold, fixes most of it.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhere Does Accumulated Depreciation Appear on the Balance Sheet?
It appears in the Non-Current Assets section, directly below the gross cost of the asset:
| Line Item | Amount |
|---|---|
| Equipment (at cost) | $120,000 |
| Less: Accumulated Depreciation | ($45,000) |
| Equipment, Net Book Value | $75,000 |
The net book value ($75,000 in this example) is what appears in the total assets calculation. The gross cost and accumulated depreciation are both shown so readers can see how much of the asset's life has been 'used up'.
How Accumulated Depreciation Builds Up Over Time
Example: A business purchases a delivery van for $60,000 with a 5-year useful life and $10,000 residual value. Using straight-line depreciation:
Annual depreciation = ($60,000 − $10,000) / 5 = $10,000/year
| Year | Gross Cost | Annual Depreciation | Accumulated Depreciation | Net Book Value |
|---|---|---|---|---|
| Year 1 | $60,000 | $10,000 | $10,000 | $50,000 |
| Year 2 | $60,000 | $10,000 | $20,000 | $40,000 |
| Year 3 | $60,000 | $10,000 | $30,000 | $30,000 |
| Year 4 | $60,000 | $10,000 | $40,000 | $20,000 |
| Year 5 | $60,000 | $10,000 | $50,000 | $10,000 (residual) |
Common Depreciation Methods
| Method | Formula | Best For |
|---|---|---|
| Straight-Line | (Cost − Residual Value) / Useful Life | Assets that generate uniform benefit each year (office furniture, fixtures) |
| Declining Balance | Net Book Value × Depreciation Rate | Assets that lose value faster early on (vehicles, computers) |
| Units of Production | (Cost − Residual) / Total Expected Units × Units This Period | Assets whose wear is usage-driven (machinery, mining equipment) |
| Sum-of-Years' Digits | Accelerated method; assigns higher depreciation in early years | Assets that are more productive in early years |
Why Accumulated Depreciation Matters
- Net book value shows the remaining carrying value of assets, important for loan collateral assessments and asset-based lending
- A fully depreciated asset (net book value = residual value) that is still in use signals it may need replacement soon or that the useful life estimate was too short
- High accumulated depreciation relative to gross cost indicates an ageing asset base, a capital expenditure cycle may be approaching
- Depreciation is a non-cash expense, it reduces profit on the income statement without reducing cash; this is why EBITDA adds it back
CLIENT QUOTE:
We had been expensing major equipment purchases as soon as we bought them, so our P&L was showing much higher expenses than it should have and our balance sheet wasn't reflecting the assets we actually owned. Profitjets moved the qualifying equipment onto the balance sheet, corrected the depreciation schedule, and adjusted the prior-period entries. That also changed our tax calculation because the deductions were recognized through the applicable depreciation treatment rather than being treated as immediate expenses.
Book a free consultation and we will reconcile it to your accounts.
FAQs
Is accumulated depreciation a liability?
No. It's a contra-asset account, meaning it sits on the asset side of the balance sheet and reduces the value of the related assets. The business doesn't owe it to anyone, so it isn't a liability.
Does accumulated depreciation reduce cash?
No. The cash was spent when the asset was bought, or is paid as loan installments. Depreciation spreads that cost over time on the income statement, and accumulated depreciation tracks the total on the balance sheet, but neither involves cash moving out of the business.
Why is my book depreciation different from my tax depreciation?
Because they follow different rules. The books usually spread cost evenly over an asset's useful life, while tax rules often allow faster deductions, including bonus depreciation and Section 179 expensing. Both are correct for their purpose, and the difference is reconciled at tax time.
What happens when an asset is fully depreciated?
It stays on the balance sheet at its original cost, with accumulated depreciation equal to cost minus salvage value, until it's sold, scrapped, or otherwise disposed of. No further depreciation is recorded, even if the business keeps using it.
Does land depreciate?
No. Land isn't considered to wear out, so it isn't depreciated. When a business buys property, the purchase price has to be split between the land and the building, and only the building portion is depreciated.

Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Asset Register Out of Date?
Book a free consultation and we will reconcile it to your accounts.