
Accounting Principles: Definition
Accounting principles are the foundational guidelines and rules that govern how financial transactions are recorded and reported. They provide a standardized framework that makes financial statements consistent, comparable, and reliable across different organizations and time periods. For accounting information to be useful, it must be accurate (free from material errors), consistent (applied the same way period to period), objective (based on verifiable evidence), and material (capturing everything significant enough to influence a financial decision).
These principles did not emerge from a single source, they evolved over decades through the work of accounting standards bodies, regulators, and professional organizations responding to the needs of investors, creditors, and the public for trustworthy financial information.
Accounting principles aren't bureaucratic rules, they're the shared language that makes financial statements trustworthy. Without them, every set of accounts would be speaking a different dialect.
Ankit Sarawagi, CPA, CA, MBA · LinkedInImportance of Accounting Principles
Without a common set of accounting principles, every business could report its finances however it found most convenient or flattering. Accounting principles prevent this by establishing:
- Standardized financial communication: A set of accounts prepared under GAAP means the same thing regardless of which company produces them.
- Transparency: Principles require disclosures that let readers understand not just the numbers but the judgments and estimates behind them.
- Fair cross-company comparisons: Investors can compare financial statements from different companies because both are prepared under the same rules.
- Regulatory compliance: Public companies must follow GAAP or IFRS; violations can trigger SEC enforcement, audit failures, and investor lawsuits.
How Do Accounting Principles Work?
In practice, accounting principles shape every step of the financial reporting process. When a transaction occurs, the accountant identifies its economic substance, not just its legal form. The transaction is then documented through journal entries that follow the double-entry system. Entries are classified into the correct accounts, assets, liabilities, equity, revenue, expenses, and finally summarized in financial statements that apply principles like matching, conservatism, and full disclosure to ensure the statements fairly represent the business's financial reality.
Accounting Principles: Examples
Accrual Principle
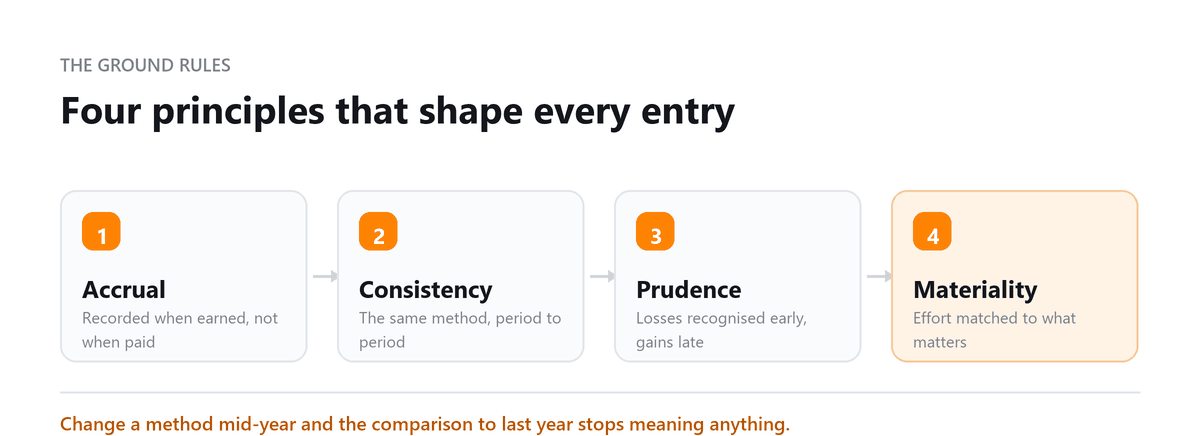
Revenue is recorded when it is earned, when goods are delivered or services rendered, not when cash is received. Similarly, expenses are recorded when they are incurred, not when the bill is paid. This principle ensures financial statements reflect economic activity in the period it occurs, giving a truer picture than cash-only tracking. Example: a consulting firm that completes a project in December records the revenue in December, even if the client pays in January.
Going Concern Principle
Accountants prepare financial statements on the assumption that the business will continue operating indefinitely unless there is substantial evidence to the contrary. This principle affects how assets are valued, they are recorded at historical cost rather than liquidation value, and how long-term obligations are classified. If a business is in genuine danger of closing, the auditor must flag this with a going-concern opinion, which triggers a range of additional disclosures.
Matching Principle
Expenses should be recognized in the same accounting period as the revenue they helped generate. This is why cost of goods sold is matched to the revenue from the sale in the same period, and why sales commissions earned in December appear as a December expense even if they are paid in January. The matching principle prevents profit manipulation through timing and ensures the income statement reflects true period performance.
Materiality Principle
Not every transaction warrants the same level of accounting precision. The materiality principle says that an item should only be separately disclosed if its omission or misstatement could influence the economic decisions of a user of the financial statements. A $50 desk purchase can be expensed immediately rather than depreciated; a $500,000 contingent liability must be disclosed. What is material depends on the size and context of the business.
Consistency Principle
Once an accounting method is chosen, FIFO inventory costing, straight-line depreciation, percentage-of-completion revenue recognition, it must be applied consistently from period to period. Changing methods without disclosure makes comparative analysis unreliable and can obscure trends. If a change is warranted, it must be disclosed in the financial statement notes with an explanation of why the change was made and its quantified impact.
Conservatism Principle
When accountants face uncertainty between two acceptable options, they should choose the one that is less likely to overstate assets or income. Losses should be recognized as soon as they are probable; gains should wait until they are realized. This principle creates a natural floor of caution in financial reporting, losses are never delayed, but revenues are never accelerated. The result is financial statements that lean toward prudence rather than optimism.
What is GAAP?
Generally Accepted Accounting Principles (GAAP) is the comprehensive rulebook governing financial reporting in the United States. Developed and maintained by the Financial Accounting Standards Board (FASB), GAAP covers everything from how revenue is recognized to how leases appear on balance sheets to what must be disclosed in financial statement notes. All U.S. public companies are required to follow GAAP, and most private companies that work with lenders or investors also prepare GAAP-compliant statements. GAAP is notably rules-based, it provides specific guidance for a wide range of industry-specific situations.
What is IFRS?
The International Financial Reporting Standards (IFRS) are issued by the International Accounting Standards Board (IASB) and adopted in more than 140 countries, including the European Union, UK, Canada, Australia, and India. IFRS is more principles-based than GAAP, it establishes broad standards and relies on professional judgment to apply them, rather than providing a rule for every scenario.
The two frameworks are increasingly converged on key topics like revenue recognition, but differences remain in areas such as inventory valuation (LIFO is permitted under GAAP but prohibited under IFRS) and treatment of certain financial instruments.
Why Choose Profitjets
Profitjets accountants are trained in both GAAP and IFRS and work across all major industries. Whether your business needs a clean set of GAAP-compliant books for lender review, help transitioning from cash to accrual accounting, or a catch-up of months of unrecorded transactions, our team brings the right principles expertise to your situation.
Conclusion
Accounting principles are the rules of the road for financial reporting. They exist not to create bureaucratic burden but to ensure that the financial statements your business produces are trustworthy, comparable, and decision-useful. Understanding the principles behind your numbers, not just the numbers themselves, is what separates a business owner who is truly financially literate from one who is merely looking at reports.
From the Profitjets Team
Profitjets has supported more than 40 businesses with accounting reviews, helping apply core accounting principles consistently across revenue, expenses, assets, and liabilities.
These reviews have helped identify timing differences, incorrect classifications, and other inconsistencies that can affect financial reporting. Across these engagements, businesses have typically uncovered 5 to 15% of recorded transactions that required reclassification or adjustment to present their financial position more accurately.
Book a free consultation and we will apply the principles consistently.
Frequently Asked Questions
Are accounting principles the same as accounting standards?
They're related but different. Principles are the broad underlying concepts, like accrual or consistency. Standards (GAAP, IFRS) are the specific rules that codify how those principles apply to particular transactions.
Does every small business have to follow GAAP?
GAAP is required for public companies and often demanded by lenders or investors. Small private businesses have more flexibility, but following GAAP principles builds credibility and makes financial statements more useful.
What happens if a business violates accounting principles?
Violations can lead to misstated financials, IRS penalties, failed audits, and loss of investor confidence. For public companies, they can trigger SEC enforcement actions.
What is the difference between GAAP and IFRS?
GAAP is the U.S. standard, more rules-based with detailed industry guidance. IFRS is the international standard, more principles-based and used in over 140 countries. Key differences include inventory valuation (LIFO allowed under GAAP only) and revenue recognition approaches.
How do I know which accounting principles apply to my business?
Your industry, size, and whether you have external investors or lenders determines which standards apply. A CPA or outsourced accounting firm can identify your specific obligations and set up compliant bookkeeping from day one.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Books Kept to the Standard?
Book a free consultation and we will apply the principles consistently.