
Payroll taxes are taxes on wages. They come in two sections, with the first being employee withholding and direct employer taxes. The former is a deduction from the gross pay that is earned by the employees, and the latter is an additional amount that the business must pay for FICA, Federal Unemployment, and State Unemployment. Knowing the difference helps with figuring out the payroll budget, ensuring tax rules are met, and staying clear from IRS penalties.
Payroll taxes are the taxes levied on wages paid partly by employees (withheld from their paycheck) and partly by employers (a separate cost on top of the employee's gross wages). Understanding which taxes are the employee's obligation and which are the employer's is critical for accurate payroll processing, correct budgeting for labour costs, and avoiding IRS penalties.
The single most costly minimum wage mistake small business owners make is paying remote or multi-location workers based on corporate headquarters rates rather than the exact municipality where the work is physically performed, it creates instant back-pay liability and triggers mandatory liquidated damages.
Ankit Sarawagi, CPA, CA, MBA · LinkedInPayroll Tax Summary: Employee vs Employer
| Tax | Employee Pays | Employer Pays | Notes |
|---|---|---|---|
| Federal Income Tax | Yes, withheld based on W-4 and tax bracket | No (employer withholds and remits, but the tax is the employee's) | Employer is responsible for accurate withholding and timely remittance |
| Social Security (OASDI) | 6.2% of wages up to wage base | 6.2% of wages up to wage base (match) | 2025 SS wage base: $176,100, verify for 2026. No SS on wages above the base. |
| Medicare (HI) | 1.45% of all wages (no cap) | 1.45% of all wages (no cap; employer match) | Additional 0.9% Medicare: employee only (above $200k); employer does NOT match |
| FUTA (Federal Unemployment) | No | 6.0% on first $7,000 per employee; effective rate 0.6% with full SUTA credit | Employer-only tax; NOT withheld from employees |
| SUTA (State Unemployment) | No (most states) | Rate varies by state and experience rating (typically 1 to 8%) | Employee-paid SUTA exists in: Alaska, New Jersey, Pennsylvania, verify your state |
| State Income Tax | Yes (in states with income tax) | No (employer withholds and remits) | No state income tax: TX, FL, NV, WA, WY, SD, AK, NH (on wages) |
| Local Income Tax | Yes (where applicable, NYC, Philadelphia, etc.) | No (employer withholds and remits) | Check if any operating city has a local income tax obligation |
Across Profitjets client payroll runs, the average employer-side payroll tax burden sits at 8.2% to 10.5% of gross wages (excluding health insurance and 401k matches)
Total Employer Cost Per Employee, The Payroll Tax Burden
The 'cost' of an employee to the employer is gross wages PLUS employer-side payroll taxes. For a $60,000/year salary:
| Cost Element | Calculation | Amount |
|---|---|---|
| Gross wages | $60,000 | |
| Social Security (employer) | $60,000 x 6.2% | $3,720 |
| Medicare (employer) | $60,000 x 1.45% | $870 |
| FUTA | $7,000 x 0.6% (net after SUTA credit) | $42 |
| SUTA (example: 2.7% new employer rate x $7,000 wage base) | $7,000 x 2.7% | $189 |
| Total employer cost | ~$64,821 (varies by state SUTA rate and base) |
Payroll Tax Filing and Deposit Requirements
| Form | Frequency | What It Reports | Due Date |
|---|---|---|---|
| Form 941 | Quarterly | Federal income tax withheld + employee and employer FICA | April 30, July 31, October 31, January 31 |
| Form 940 | Annual | Federal Unemployment Tax (FUTA) | January 31 (or February 10 if all deposits made on time) |
| W-2 | Annual | Employee wages, withholding, and benefits | To employees by January 31; to SSA by January 31 |
| 1099-NEC | Annual | Payments to contractors ($600+ threshold) | To contractors and IRS by January 31 |
| State equivalents | Varies by state | State income tax withheld + state unemployment | Per each state's requirements, check state revenue/labor agency |
The most common payroll tax error found during initial client onboarding is misclassifying multi-state remote employees for SUTA and local tax withholding, resulting in unexpected retroactive tax liabilities.
Payroll Tax Deposit Schedules
The IRS requires employers to deposit withheld federal income tax and FICA taxes (employee + employer) on one of two schedules, determined by the employer's lookback period liability:
| Schedule | Who It Applies To | Deposit Deadline |
|---|---|---|
| Monthly | Employers whose total 941 tax liability in the lookback period was $50,000 or less | 15th of the following month |
| Semi-weekly | Employers whose total 941 tax liability in the lookback period exceeded $50,000 | Wednesday/Friday depending on pay date (specific IRS table applies) |
| Next business day | Any employer with a single-day deposit obligation of $100,000 or more | Next business day after the payroll run |
For instance, Profitjets onboarded an e-commerce startup that expanded their team from 2 to 8 employees without accounting for the employer-side payroll tax match and state unemployment taxes. By Q2, they faced an unexpected $14,000 cash flow shortfall when Form 941 deposits and state SUTA bills came due simultaneously.
We restructured their payroll budgeting model to auto-reserve 10% above gross payroll each pay period into a dedicated tax escrow account, preventing future cash crunches and ensuring 100% on-time filings.
FAQs
The True Cost of a Hire
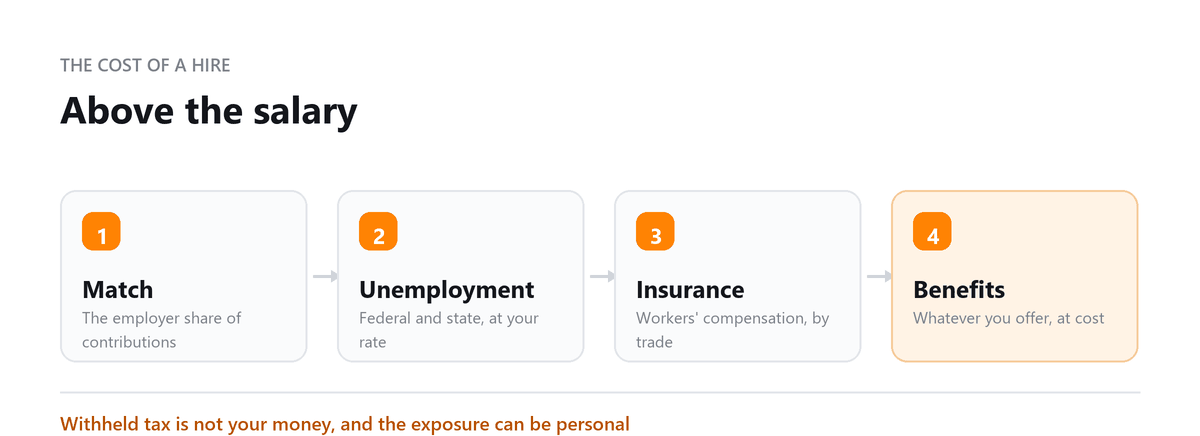
The salary is the number that gets negotiated and it is not the number to budget. The fully loaded cost of an employee is materially higher, and the difference varies by state.
- The employer's share of social security and Medicare contributions
- Federal unemployment tax, and state unemployment at your own experience rate
- Workers' compensation insurance, priced by the work being done
- Any state-specific programmes, which several states operate and others do not
- The employer cost of benefits offered, including any retirement contribution
Working this out once for a typical role, in each state you employ in, gives you a multiplier you can apply when planning. It is also the figure to use when pricing work, since a quote built on bare salary is systematically too low.
Deposit Schedules and Where the Risk Sits
Withheld taxes are not your money. They are held on behalf of employees and the government, and the rules around remitting them are stricter than for ordinary business debts.
The deposit schedule is set by the size of your payroll rather than chosen, and it is reassessed periodically, so a growing business can move to a more frequent schedule without noticing. There is also a threshold above which a deposit becomes due very quickly rather than on the normal cycle.
Penalties for late deposits are tiered by how late they are, and responsible individuals can be held personally liable for amounts withheld and not remitted. That personal exposure is what makes this different from other payables, and it is why the deposit dates belong in a calendar rather than in someone's memory. Current schedules and thresholds are published by the IRS.
Reconciling Payroll to the Ledger
Payroll is usually the largest expense in a service business and the one least often reconciled, because the provider's reports look authoritative and the ledger figure is assumed to agree.
A quarterly reconciliation covers gross wages against the wage expense accounts, employer taxes against the payroll tax accounts, net pay against the actual bank debits, and the liability accounts for withheld amounts, which should clear to close to nil once payments are made.
Doing it quarterly takes under an hour. Doing it once a year takes most of a day and finds errors that have already reached four quarterly returns, which means correcting them involves amended filings rather than a journal.
Book a free consultation and we will give you the loaded cost.
FAQs
What payroll taxes does an employer pay?
Employers generally pay the employer share of Social Security and Medicare taxes, as well as federal and state unemployment taxes. For 2026, the employer Social Security rate is 6.2% on wages up to the $184,500 wage base, while Medicare is 1.45% on all covered wages. FUTA is generally 6% on the first $7,000 of wages per employee, with eligible employers potentially receiving a credit that reduces the effective rate to 0.6%. State unemployment tax (SUTA) varies by state and employer.
What is the employer Social Security tax rate?
The employer Social Security tax rate is 6.2%, matching the employee's 6.2% share for a combined rate of 12.4%. For 2026, the Social Security wage base is $184,500. Once an employee's wages exceed this amount during the year, the employer generally no longer owes Social Security tax on additional wages for that employee.
Does an employer pay Medicare tax on all employee wages?
Yes. The employer Medicare tax rate is generally 1.45% on all covered employee wages, with no annual wage cap. Unlike the Additional Medicare Tax, which may apply to certain employees, employers generally do not match the employee's 0.9% Additional Medicare Tax.
What is FUTA tax, and who pays it?
FUTA, or Federal Unemployment Tax Act tax, is generally paid by employers rather than withheld from employee wages. The standard FUTA rate is 6% on the first $7,000 of wages per employee, but eligible employers can generally receive a credit for state unemployment taxes paid, reducing the effective federal rate to 0.6%.
Do employers pay federal and state income taxes for employees?
Employers generally withhold federal and applicable state or local income taxes from employees wages and remit those amounts to the appropriate tax authorities. These income taxes are employee obligations rather than employer payroll-tax expenses. Employers are responsible for correctly withholding, depositing, and reporting the amounts.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Budgeting for a Hire?
Book a free consultation and we will give you the loaded cost.